Malaysia is the first ASEAN country with an official government costing of its CBAM exposure.
In a parliamentary reply reported on August 6, 2026 by Carbon Pulse and GMK Center, the Ministry of Investment, Trade and Industry (MITI) cited a Malaysian Steel Institute estimate putting the 2026 CBAM compliance bill for the country's iron and steel industry at approximately MYR 970.7 million, about USD 237 million.
Behind that figure sits a concentrated trade exposure. MITI's reply put Malaysia's iron and steel exports to the EU at about 752,000 tonnes in 2025, out of about 6.0 million tonnes exported worldwide (Bernama, August 4, 2026).
Eurostat's import statistics, which record country of origin, show 628 thousand tonnes of CBAM-covered iron and steel (Annex I codes) from Malaysia in 2025, worth €523.5 million (EU27 imports, Comext DS-045409, extracted October 12, 2026).
Since Regulation (EU) 2023/956 entered its definitive phase on January 1, 2026, every EU-bound tonne of that volume generates a certificate obligation on the EU importer, and Malaysia has no carbon price in force that could offset any part of it.
This article covers the sectors that pull Malaysian exporters into CBAM scope, what the MYR 970.7 million estimate means in practice, why no Article 9 deduction basis exists for Malaysia today, the four-part response MITI has announced, and the compliance steps that reduce the cost for Malaysian producers and their EU buyers.
Our news report on Malaysia's USD 237 million CBAM steel bill covers the parliamentary reply itself in full.
Which CBAM Sectors Apply to Malaysian Exports?
Steel is the dominant CBAM exposure for Malaysia, with aluminium as the second relevant category.
Of the six sectors covered by Regulation (EU) 2023/956, iron and steel, cement, aluminium, fertilizers, electricity, and hydrogen, only iron and steel reaches the EU from Malaysia at the scale that produced a national cost estimate, and aluminium products form the second CBAM-relevant export line.
Malaysia does not export electricity to the EU, and the official exposure estimate does not concern cement, fertilizer, or hydrogen flows.
Eurostat's import statistics show the same split. Of the €911.9 million of CBAM-covered goods the EU27 imported from Malaysia in 2025, iron and steel made up 57.4%, aluminium 41.5% (€378.1 million, 127 thousand tonnes) and cement 1.1% (Eurostat Comext, 2025).
For steel, CBAM prices direct emissions only, since iron and steel is listed in Annex II of the regulation. The financial exposure per tonne depends on the production route: the blast furnace-basic oxygen furnace (BF-BOF) route carries approximately 2.0 tCO₂ per tonne, while electric arc furnace (EAF) scrap-based production carries approximately 0.5 tCO₂ per tonne.
The steel sector under CBAM spans CN codes across Chapters 72 and 73, from semi-finished products through flat-rolled products to downstream steel articles.
For aluminium, CBAM also prices direct emissions only, including perfluorocarbons from the electrolysis process, with primary aluminium carrying approximately 1.5 tCO₂ per tonne in direct emissions.
Malaysian producers exporting covered aluminium products face the same data and certificate mechanics as steel exporters, at a lower per-tonne emission factor. The full authorization, declaration, and certificate workflow is covered in the EU CBAM guide.
The 50-tonne annual de minimis threshold exempts EU importers below that mass per year, but industrial steel and aluminium volumes sit far above it, so the exemption offers Malaysia's export trade no practical relief.
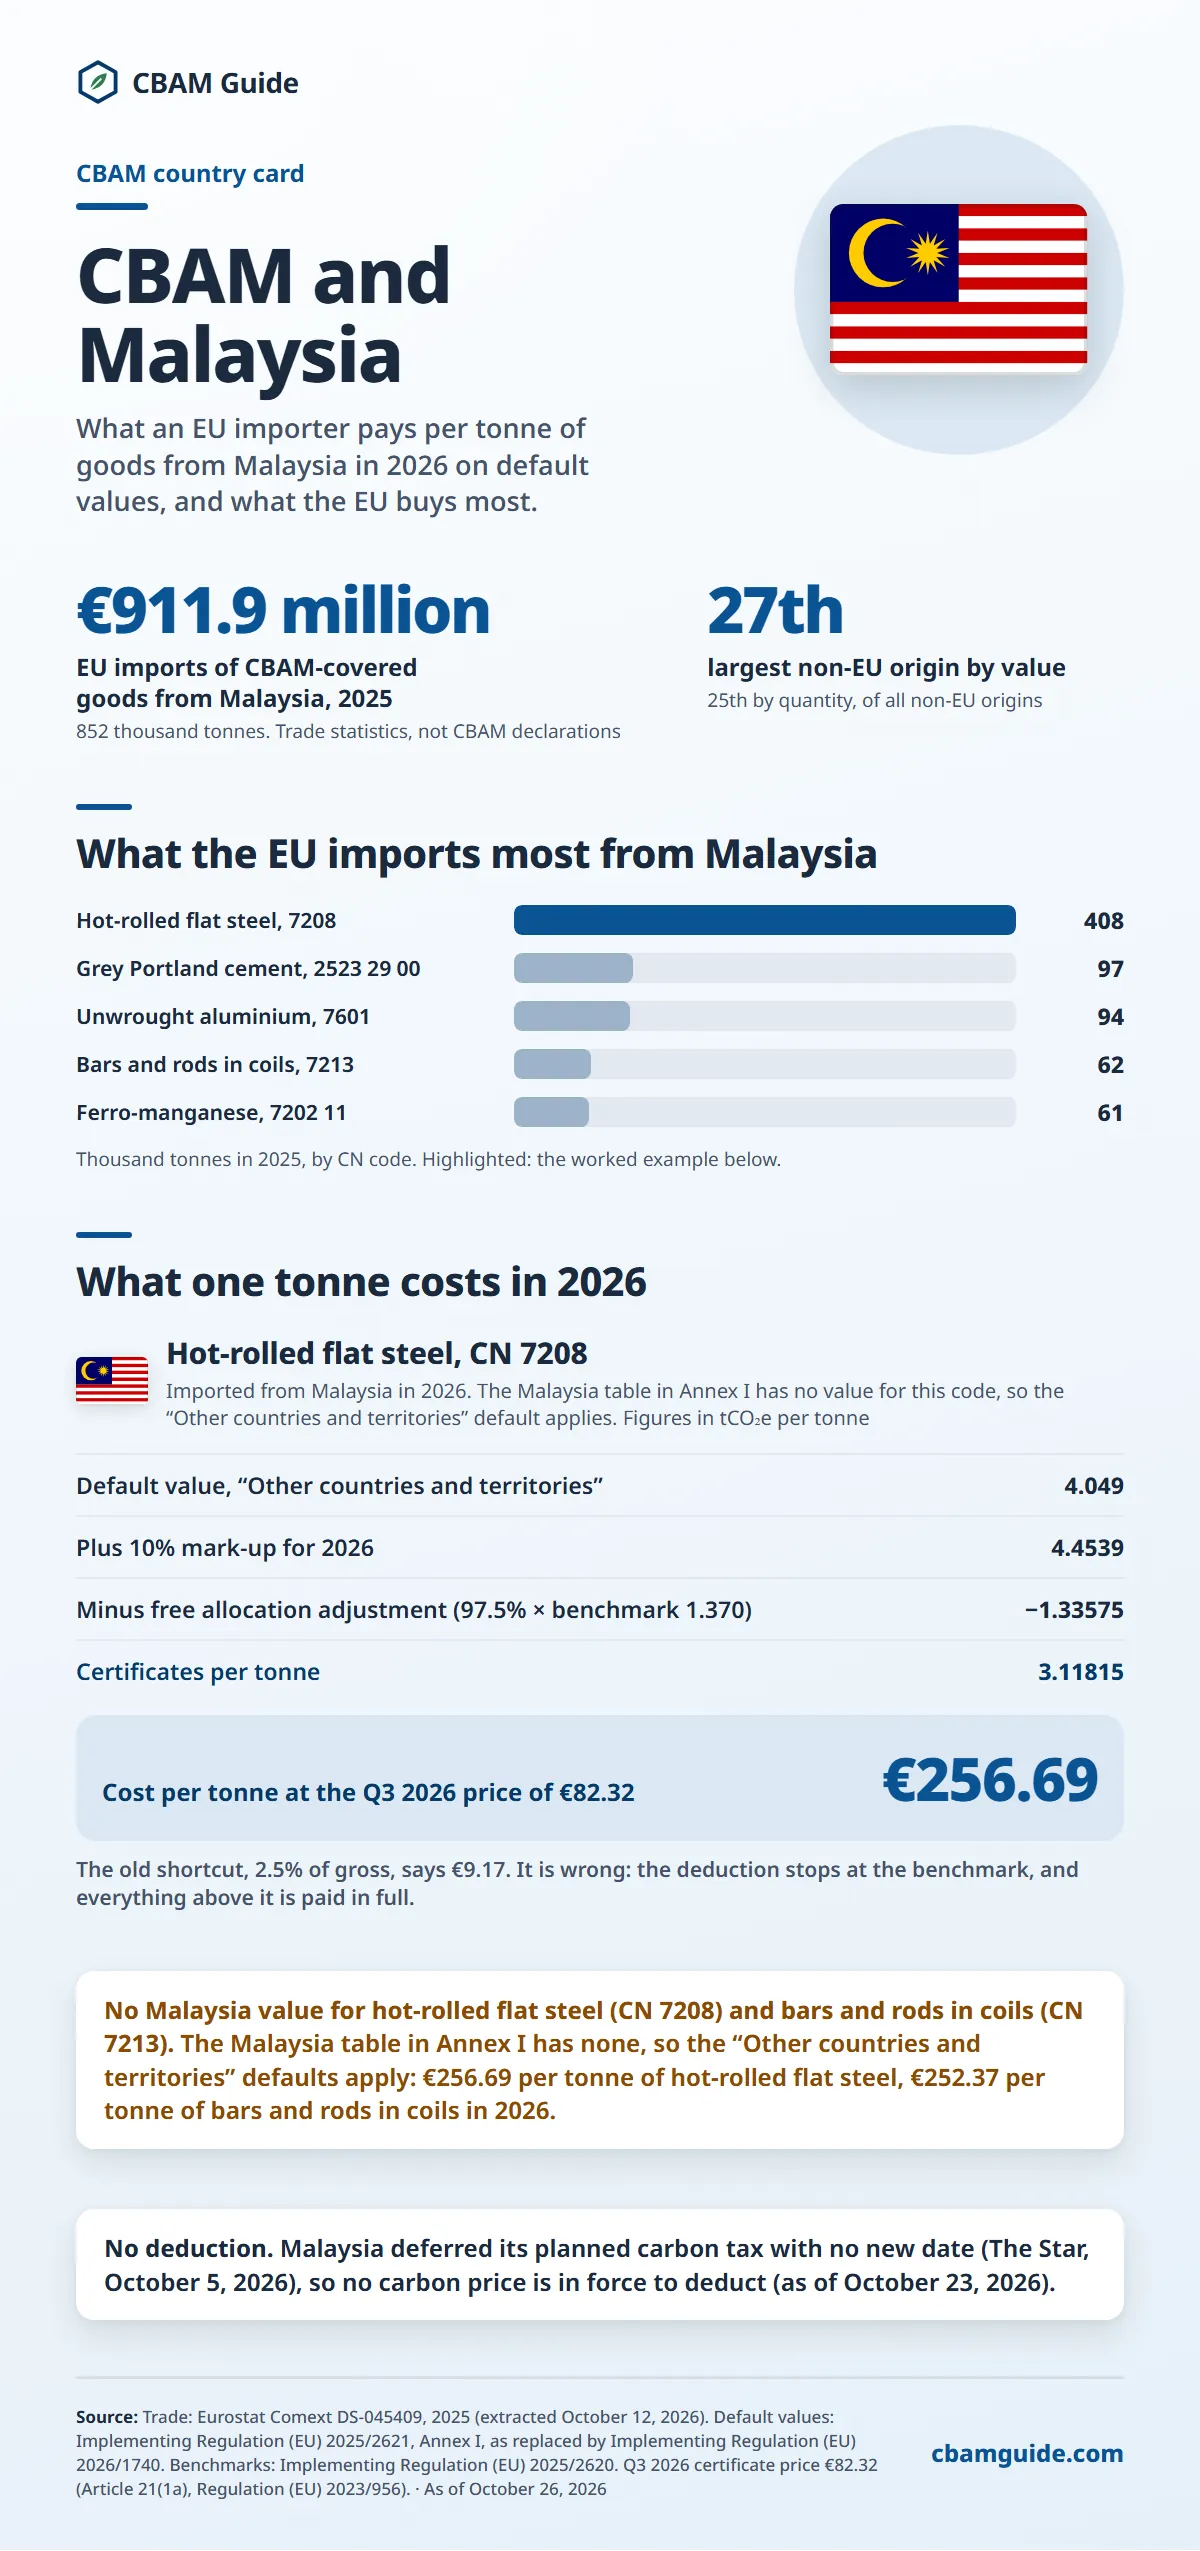
Text version of this infographic
- €911.9 million: EU imports of CBAM-covered goods from Malaysia, 2025 (852 thousand tonnes. Trade statistics, not CBAM declarations)
- 27th: largest non-EU origin by value (25th by quantity, of all non-EU origins)
What the EU imports most from Malaysia
- Hot-rolled flat steel, 7208: 408
- Grey Portland cement, 2523 29 00: 97
- Unwrought aluminium, 7601: 94
- Bars and rods in coils, 7213: 62
- Ferro-manganese, 7202 11: 61
Thousand tonnes in 2025, by CN code. Highlighted: the worked example below.
What one tonne costs in 2026
Hot-rolled flat steel, CN 7208 (Imported from Malaysia in 2026. The Malaysia table in Annex I has no value for this code, so the “Other countries and territories” default applies. Figures in tCO₂e per tonne)
- Default value, “Other countries and territories”: 4.049
- Plus 10% mark-up for 2026: 4.4539
- Minus free allocation adjustment (97.5% × benchmark 1.370): −1.33575
- Certificates per tonne: 3.11815
Cost per tonne at the Q3 2026 price of €82.32: €256.69
The old shortcut, 2.5% of gross, says €9.17. It is wrong: the deduction stops at the benchmark, and everything above it is paid in full.
No Malaysia value for hot-rolled flat steel (CN 7208) and bars and rods in coils (CN 7213). The Malaysia table in Annex I has none, so the “Other countries and territories” defaults apply: €256.69 per tonne of hot-rolled flat steel, €252.37 per tonne of bars and rods in coils in 2026.
No deduction. Malaysia deferred its planned carbon tax with no new date (The Star, October 5, 2026), so no carbon price is in force to deduct (as of October 23, 2026).
What Did MITI Tell Parliament About Malaysia's CBAM Cost?
MITI cited a Malaysian Steel Institute estimate of approximately MYR 970.7 million, about USD 237 million, as the 2026 CBAM compliance cost for Malaysia's iron and steel industry. The figure appeared in a parliamentary reply and was reported internationally by Carbon Pulse and GMK Center on August 6, 2026.
It is the first official costing of national CBAM exposure published by any ASEAN government; the region's previous numbers had come from industry bodies and consultancies rather than a government-endorsed estimate.
The table below sets out the key figures from the reply.
| Metric | Value |
|---|---|
| Estimated 2026 CBAM compliance cost, iron and steel | ~MYR 970.7 million (about USD 237 million) |
| Source of the estimate | Malaysian Steel Institute, cited by MITI in a parliamentary reply |
| Iron and steel exports to the EU, 2025 (MITI) | ~752,000 tonnes |
| Total iron and steel exports, 2025 (MITI) | ~6.0 million tonnes |
| EU share of export volume (MITI) | ~12.5 percent |
| For comparison, not part of the reply: EU27 imports of CBAM-covered iron and steel from Malaysia, 2025 (Eurostat Comext, extracted October 12, 2026) | 628 thousand tonnes, €523.5 million |
An official number changes the policy conversation in a way industry estimates do not. It commits the government to a position on the size of the problem, anchors the budget case for the response measures described below, and gives Malaysia a concrete figure to bring into any bilateral engagement with the EU.
Neighboring exporters face the same mechanism without an equivalent official costing: the CBAM Vietnam and CBAM Indonesia guides track two regional peers whose published exposure figures trace to industry and analyst work.
What Does CBAM Cost Per Tonne of Malaysian Steel?
On default values, Malaysian hot-rolled flat steel (CN 7208), the product that makes up most of the trade, costs €256.69 per tonne for 2026 imports, because Malaysia's Annex I table has no row for it and the "Other Countries and Territories" value applies.
Aluminium has Malaysia-specific default values. The table below uses Annex I to Implementing Regulation (EU) 2025/2621, as replaced by Implementing Regulation (EU) 2026/1740, and the official Q3 2026 certificate price of €82.32, published October 5, 2026.
Hot-rolled flat steel is the good to anchor on. The EU27 imported 408 thousand tonnes of it from Malaysia in 2025, worth €196.0 million, 3.6% of extra-EU imports under CN 7208 and the eighth-largest origin; unwrought aluminium (CN 7601) was 94 thousand tonnes and €246.7 million.
Imports of semi-finished steel (CN 7207) from Malaysia were nil, so that product is not costed here (Eurostat Comext DS-045409, extracted October 12, 2026).
| Product (CN code) | Default value (tCO₂e/t) | Default plus 2026 mark-up | Benchmark | Certificates per tonne 2026 | Cost per tonne 2026 at €82.32 | Cost per tonne 2030 at constant price |
|---|---|---|---|---|---|---|
| Hot-rolled flat steel (CN 7208) | 4.049 ("Other Countries and Territories") | 4.454 | 1.370 | 3.118 | €256.69 | €375.23 |
| Unwrought aluminium (CN 7601) | 1.700 (Malaysia) | 1.870 | 1.423 | 0.483 | €39.73 | €121.60 |
Certificates per tonne equal the default plus the mark-up, minus the free allocation adjustment (CBAM factor × cross-sectoral correction factor × the Column B benchmark of Implementing Regulation (EU) 2025/2620). Inputs for 2026: mark-up 10%, CBAM factor 97.5%, correction factor 100%, blast furnace route (C) for steel and primary route (K) for aluminium. The 2030 column uses a 30% mark-up and a CBAM factor of 51.5%, with the price and the benchmarks held constant; the benchmarks may be updated from 2027. Figures are rounded to three decimals and costs are computed from the unrounded figures.
The legal CBAM factor is the share of free allocation retained: 97.5% in 2026, 51.5% in 2030 and none from 2034. The adjustment it produces is a fixed quantity per tonne, so every tonne of CO₂e above the benchmark, the whole mark-up included, is charged at the full certificate price from the first year.
The structural consequence for Malaysia is that the MYR 970.7 million estimate describes the entry year of a cost curve, not its peak: at a constant price, the default-value cost of hot-rolled flat steel is about 46% higher for 2030 imports than for 2026 imports.
Certificate sales begin February 1, 2027, and the first annual CBAM declaration, covering calendar year 2026 imports, is due from EU declarants by September 30, 2027.
Why Malaysia Has No Article 9 Deduction Basis Today
Malaysia has no carbon price in force, so there is no basis for an Article 9 deduction on Malaysian goods as of October 12, 2026. Article 9 of Regulation (EU) 2023/956 permits the EU importer to deduct a carbon price effectively paid in the country of origin from the CBAM certificate obligation.
Where no such price exists, the deduction has nothing to work with: the liability equation reduces to embedded emissions minus the free allocation adjustment, multiplied by the certificate price, and embedded emissions is the only variable the Malaysian producer controls.
A carbon tax was announced in the Budget 2026 speech of October 10, 2025 for introduction in 2026, starting with the iron, steel and energy sectors.
On October 5, 2026, The Star reported Natural Resources and Environmental Sustainability Minister Arthur Joseph Kurup saying the government had deferred the tax and would not implement it this year, with no new start date given.
The Budget 2027 speech of October 9, 2026 does not mention a carbon tax. Separately, no third-country carbon price is formally recognized under Article 9 as of October 12, 2026, because the implementing rules are still a draft.
This distinguishes Malaysia from regional peers building toward a deduction pathway. Vietnam began a pilot ETS in August 2025 that covers steel production, and Indonesia has operated a mandatory carbon market for power generation since 2023; neither is recognized under Article 9, but both have a domestic pricing instrument to develop.
Malaysia's equivalent building block is the national MRV system MITI has announced, which addresses the data half of the problem rather than the carbon price half.
A measurement, reporting, and verification framework produces the verifiable installation-level emissions data that both CBAM compliance and any future carbon pricing scheme require, but an MRV system is not a carbon price and creates no deduction by itself.
Certificate price alerts and the regulatory changes that matter. Get weekly updates on what happens regarding anything CBAM-related. No spam, unsubscribe anytime.
We store only your email address for these alerts. Privacy policy
MITI's Four-Part Response to CBAM
MITI's announced response rests on four measures: building a national MRV system, accelerating industrial decarbonisation, backing affected producers politically and financially, and negotiating with the EU for "fair treatment for developing countries." The four measures, as described in the parliamentary reply and the subsequent Carbon Pulse and GMK Center reporting, are listed below.
- A national MRV system. A Malaysian measurement, reporting and verification framework would give steel and aluminium producers installation-level emissions data in a form EU declarants can use, which is the raw material of every CBAM cost-reduction strategy available to a country without a domestic carbon price.
- Accelerated decarbonisation. Energy efficiency improvements and greater renewable energy use cut the embedded emissions attached to each exported tonne, and with them the certificate liability that the EU importer prices into the purchase contract.
- Political and financial support. The government has committed to backing the affected industry's transition politically and financially.
- Negotiation with the EU. Malaysia is pressing for "fair treatment for developing countries" in how the mechanism is applied.
The negotiation track places Malaysia inside the wider debate over CBAM and developing countries, which runs through UN climate forums, WTO argument, and bilateral diplomacy. The MRV and decarbonisation tracks, by contrast, work inside the mechanism's own logic: they lower the number the certificate price multiplies, regardless of what the diplomatic engagement yields.
What Should Malaysian Exporters Do Now?
Verified actual emissions data is the main cost lever available to Malaysian exporters, because the alternative is marked-up default values.
Where a producer provides no verified installation data, the EU declarant falls back on CBAM default values under Implementing Regulation (EU) 2025/2621, which carry a mark-up of 10% on the default value in 2026, rising to 20% in 2027 and 30% from 2028 onward.
An efficient installation providing verified actuals typically undercuts the marked-up default, which is precisely the incentive the mark-up schedule is designed to create.
The four compliance steps most relevant for Malaysian producers are listed below.
- Set up installation-level monitoring following the Commission's sector guidance. On August 14, 2026 the Commission published ten guidance documents for the definitive period, including sector-specific guides for iron and steel and for aluminium, a quick guide for non-EU operators, and a methods document for calculating embedded emissions. Our report on the ten CBAM guidance documents lists the full series. These documents are the how-to for producing the 2026 dataset that EU buyers will declare.
- Compare actual emissions against the applicable default values per CN code. The comparison quantifies what verified data is worth for the specific installation and product mix, and it determines whether the verification investment pays for itself in the first declaration cycle.
- Deliver the data in the format EU declarants can use. The CBAM data requirements for exporters guide covers the reporting structure, and registering the installation on the CBAM Operators Portal lets one verified upload serve every EU customer relationship simultaneously.
- Plan for verification early. An accredited verifier must physically visit the production installation, and the 2026 monitoring year data must be verifiable in time for the September 30, 2027 declaration deadline that EU importers face. As of November 12, 2026, seven verification bodies are documented as accredited by five national accreditation bodies (ESYD in Greece, Accredia in Italy, Swedac in Sweden, RvA in the Netherlands and BELAC in Belgium), none of them established in Malaysia, and the Commission's official list of accredited verifiers is still unpublished.
Malaysia's planned national MRV system points in the same direction as these steps. Once operational, it would standardize the monitoring data Malaysian installations produce, lowering the per-producer cost of exactly the data chain that steps 1 through 4 describe.
Until then, producers that want outside help can compare eight named providers that state a CBAM service and have a confirmed tie to Malaysia in the directory of CBAM consultants in Malaysia.
Frequently Asked Questions: CBAM Malaysia
How much will CBAM cost Malaysia's steel industry?
Approximately MYR 970.7 million, about USD 237 million, in 2026, according to a Malaysian Steel Institute estimate cited by MITI in a parliamentary reply and reported by Carbon Pulse and GMK Center on August 6, 2026. The estimate covers the iron and steel industry, which by MITI's figures exported about 752,000 tonnes to the EU in 2025 out of about 6.0 million tonnes worldwide. Eurostat records 628 thousand tonnes of CBAM-covered iron and steel imported from Malaysia in 2025, worth €523.5 million (Comext DS-045409, extracted October 12, 2026).
Do Malaysian exporters pay CBAM directly?
No. The certificate obligation falls on the EU-based authorized CBAM declarant, the importer of record, under Regulation (EU) 2023/956. The cost reaches Malaysian producers commercially: EU buyers factor certificate costs into purchase prices and prefer suppliers whose verified emissions data lowers the certificate bill.
Can Malaysian exporters claim an Article 9 deduction?
No. Malaysia has no carbon price in force as of October 12, 2026: the carbon tax planned for the iron, steel and energy sectors was deferred with no new start date, as The Star reported on October 5, 2026. No carbon price is therefore effectively paid in Malaysia that an EU importer could deduct under Article 9. The national MRV system MITI has announced would build emissions data infrastructure, but it is not a carbon pricing scheme and creates no deduction basis by itself.
Which Malaysian exports are covered by CBAM?
Iron and steel is Malaysia's largest CBAM exposure: EU27 imports of CBAM-covered iron and steel from Malaysia were 628 thousand tonnes and €523.5 million in 2025, and aluminium followed with 127 thousand tonnes and €378.1 million (Eurostat Comext DS-045409, extracted October 12, 2026). Both sectors are priced on direct emissions only under Annex II of Regulation (EU) 2023/956, so the certificate cost tracks the production route's direct emission factor.
What happens if a Malaysian producer provides no emissions data?
The EU importer falls back on default values from Implementing Regulation (EU) 2025/2621, which carry a mark-up of 10% on the default value in 2026, rising to 20% in 2027 and 30% from 2028 onward. For most efficient installations, verified actual data produces a lower certificate cost than marked-up defaults, which is what makes monitoring and verification commercially worthwhile.
Non-EU exporters across all sectors assess their CBAM exposure using the same framework. The non-EU exporters compliance hub covers authorization timelines, data submission requirements, and strategic options applicable to producers in all six CBAM sectors.