The EU CBAM timeline spans 11 years, from October 1, 2023 (when the first reporting obligations activated) to January 1, 2034 (when free EU ETS allocations for CBAM sectors reach zero). Understanding this timeline is mandatory for every importer of iron and steel, cement, aluminium, fertilizers, electricity, and hydrogen into the EU customs territory.
The EU CBAM guide covers the full mechanism and the CBAM guide for importers the obligations step by step; this page covers every date, every deadline, and the regulation article behind each one.
What Is the CBAM Implementation Timeline?
The CBAM implementation timeline is the sequence of legally binding deadlines under Regulation (EU) 2023/956, as amended by Regulation (EU) 2025/2083, governing how the EU Carbon Border Adjustment Mechanism phases in from a reporting-only transitional period through to full financial operation by 2034.
The timeline spans two major phases: the transitional period (October 1, 2023 to December 31, 2025), during which importers reported emissions with no financial obligation, and the definitive phase (January 1, 2026 onward), in which authorized declarants purchase and surrender CBAM certificates priced at the EU ETS carbon price.
The critical 2025 Omnibus amendment (CBAM Omnibus Regulation (EU) 2025/2083) shifted the most consequential deadlines, including extending the first CBAM declaration deadline from May 31, 2027 to September 30, 2027, and delaying certificate sales from January 1, 2026 to February 1, 2027.
Complete CBAM Timeline: Every Key Date and Deadline
The 16 key CBAM dates below span every major milestone in the EU CBAM timeline, from the transitional start through full phase-in. Each row includes the regulation article behind it.
| Date | Milestone | Regulation Reference |
|---|---|---|
| October 1, 2023 | Transitional period begins; quarterly reporting obligations activate | Article 32, Reg. (EU) 2023/956 |
| January 31, 2024 | First quarterly CBAM report due (covering Q4 2023) | Article 35(1), Reg. (EU) 2023/956; IR (EU) 2023/1773 |
| January 1, 2025 | Only the EU calculation methodology accepted; the derogation for other monitoring and reporting methods ran until December 31, 2024 | Article 4(2), IR (EU) 2023/1773 |
| December 31, 2025 | Transitional period ends; the last quarterly report covers Q4 2025 and was due January 31, 2026 | Articles 32 and 35(1), Reg. (EU) 2023/956; IR (EU) 2023/1773 |
| January 1, 2026 | Definitive phase begins; financial obligations activate; all 6 sectors simultaneously | Article 36(2)(b), Reg. (EU) 2023/956 |
| March 31, 2026 | Last date to apply for authorization and keep importing provisionally until the decision | Article 17(7a), inserted by Reg. (EU) 2025/2083 |
| July 31, 2026 | Correction to the default values annexes published in the Official Journal, applying retroactively from January 1, 2026 | IR (EU) 2026/1740 |
| September 1, 2026 | Accredited verifiers can request registration in the CBAM Registry from this date | Article 10a(1), inserted by Reg. (EU) 2025/2083 |
| February 1, 2027 | Certificate sales begin via Common Central Platform | Article 20(1), as amended by Reg. (EU) 2025/2083 |
| March 31, 2027 | First quarterly holding check, covering goods imported since January 1, 2027 | Article 22(2); Article 36(2)(c) |
| September 30, 2027 | First CBAM declaration due; covers calendar year 2026 imports | Article 6, as amended by Reg. (EU) 2025/2083 |
| October 31, 2027 | Deadline to request buyback of excess certificates; certificates bought in 2027 for 2026 emissions can only be repurchased in 2027 | Article 23(1) and (2a), as amended by Reg. (EU) 2025/2083 |
| November 1, 2027 | Cancellation of certificates purchased for 2026 emissions | Article 24(2) |
| September 30 (annual) | Ongoing annual CBAM declaration deadline for each preceding year | Article 6, Reg. (EU) 2023/956 |
| January 1, 2028 | Proposed: ~180 downstream steel- and aluminium-intensive products added to scope (pending co-legislator approval of COM(2025)989) | COM(2025)989 |
| January 1, 2034 | Free EU ETS allocation for CBAM sectors reaches 0%; full financial phase-in complete | Article 10a(1a), Directive 2003/87/EC as amended |
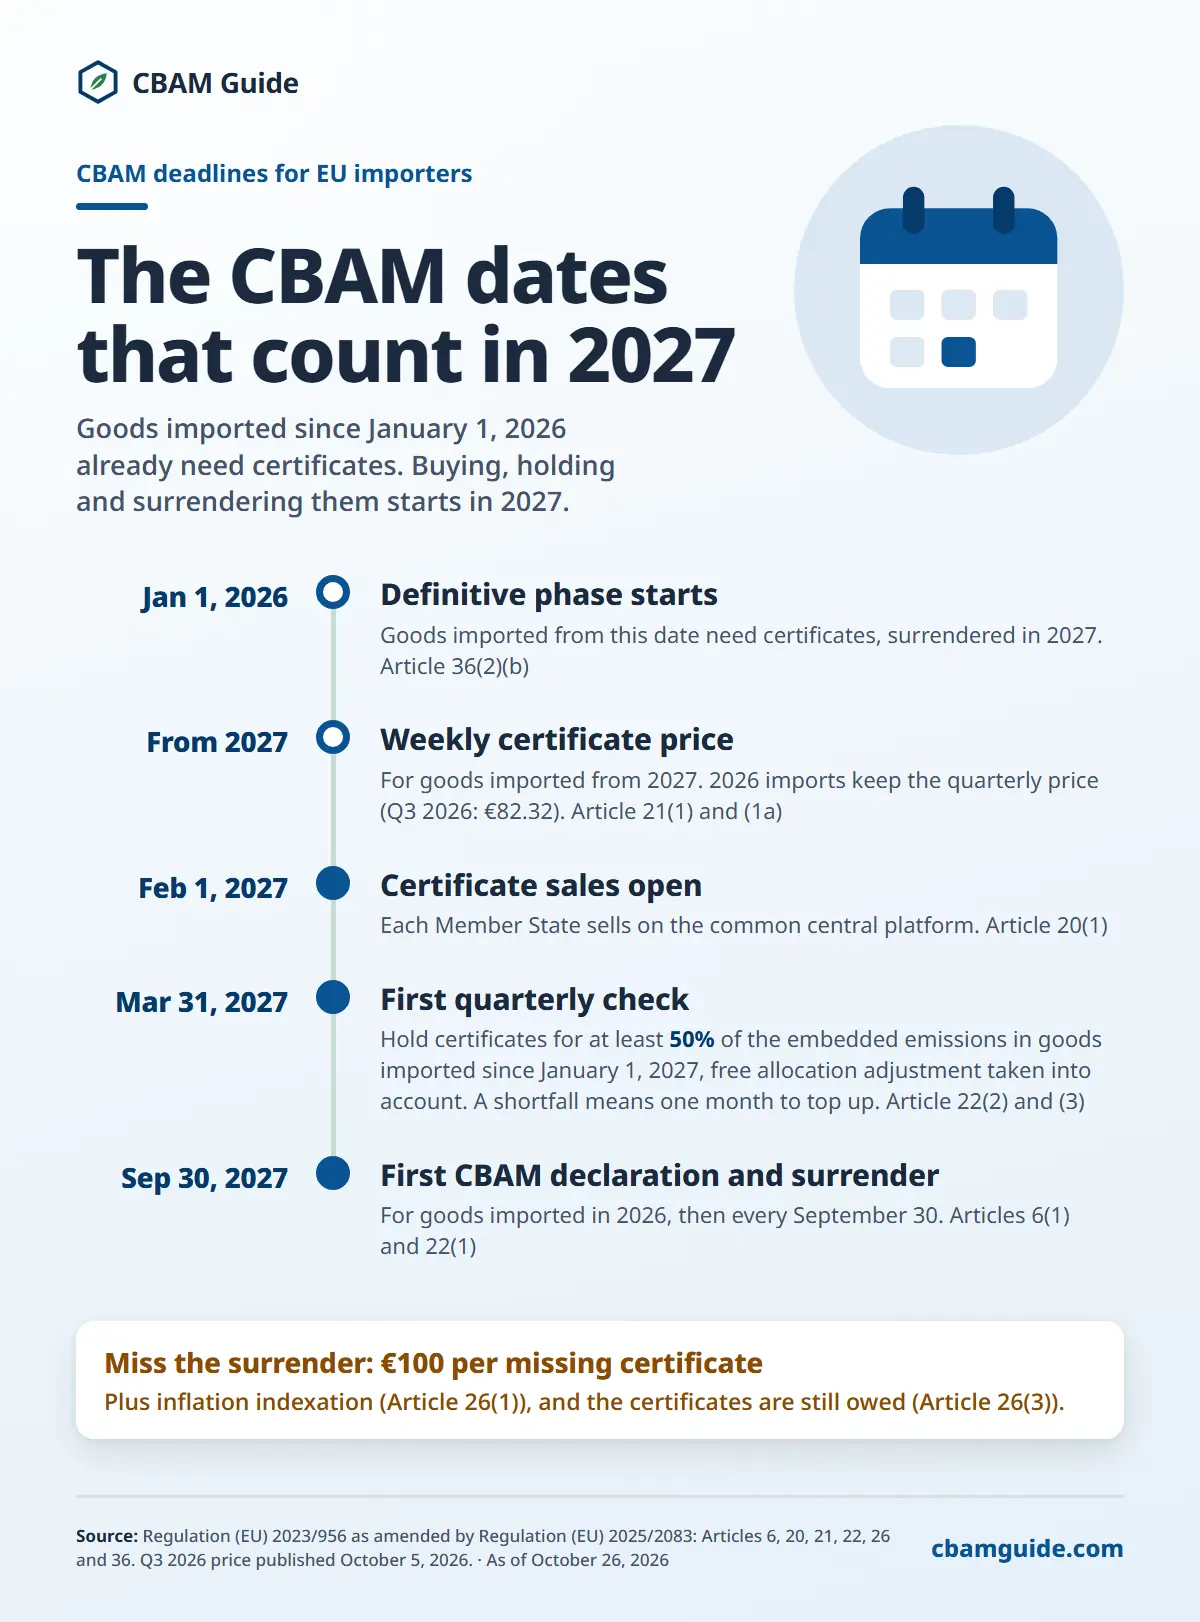
Text version of this infographic
- Jan 1, 2026: Definitive phase starts. Goods imported from this date need certificates, surrendered in 2027. Article 36(2)(b)
- From 2027: Weekly certificate price. For goods imported from 2027. 2026 imports keep the quarterly price (Q3 2026: €82.32). Article 21(1) and (1a)
- Feb 1, 2027: Certificate sales open. Each Member State sells on the common central platform. Article 20(1)
- Mar 31, 2027: First quarterly check. Hold certificates for at least 50% of the embedded emissions in goods imported since January 1, 2027, free allocation adjustment taken into account. A shortfall means one month to top up. Article 22(2) and (3)
- Sep 30, 2027: First CBAM declaration and surrender. For goods imported in 2026, then every September 30. Articles 6(1) and 22(1)
Miss the surrender: €100 per missing certificate: Plus inflation indexation (Article 26(1)), and the certificates are still owed (Article 26(3)).
The Transitional Period: October 2023 to December 2025
The CBAM transitional period ran from October 1, 2023 to December 31, 2025 and carried zero financial obligation. Importers of the 6 Annex I sectors submitted quarterly reports disclosing the quantity, origin, and embedded emissions of their CBAM goods, but purchased no certificates and paid no charges.
The legal basis is Article 32 of Regulation (EU) 2023/956, with the detailed reporting mechanics set out in Implementing Regulation (EU) 2023/1773.
Three routes existed during the transitional period under IR 2023/1773: the EU methodology using actual production data; until December 31, 2024, other monitoring and reporting methods of similar coverage and accuracy (Article 4(2)); and until July 31, 2024, other methods including the default values the Commission published for the transitional period, for importers that lacked the full data (Article 4(3)).
For the four quarterly reports of 2025 only the EU methodology remained, with estimates allowed for up to 20% of the total embedded emissions of complex goods (Article 5). The last report, for the fourth quarter of 2025, was due on January 31, 2026.
The transitional period served as a data-gathering and system-readiness phase. Over 12,000 authorization applications were submitted before the definitive phase launched, and more than 4,100 operators had received authorization as of the January 7, 2026 snapshot; both figures kept rising through the first half of 2026 as competent authorities worked through backlogs, with DEHSt reporting in June 2026 that incomplete applications and missing evidence remained the leading cause of delay for applications still pending.
Non-reporting during the transitional period carried penalties of €10–50 per tonne CO₂e unreported under Article 16 of IR (EU) 2023/1773, significantly below the definitive phase penalty of €100 per tonne CO₂e before indexation.
The Definitive Phase: January 2026 Onward
The definitive CBAM phase began on January 1, 2026, activating the full financial obligation for importers of all 6 Annex I sectors simultaneously. From this date, only authorized CBAM declarants may import CBAM goods into the EU (Article 4), with the authorization procedure set out in IR (EU) 2025/486.
A person other than an authorized declarant who brings in goods without complying faces three to five times the Article 26(1) penalty for each certificate not surrendered, which is €300 to €500 before indexation (Article 26(2)). Despite recurring searches asking is CBAM delayed to 2027, this January 2026 start date has not moved.
The CBAM deadline most important for 2026 importers falls on March 31, 2026: this is the last date to submit a provisional authorization application while continuing to import.
Importers who applied by March 31, 2026 may continue importing pending their competent authority's decision, which can take up to 120 days from a complete application under Article 4(1) of IR 2025/486.
Certificates for goods imported in 2026 are priced at the quarterly average of EU ETS auction closing prices for the quarter of import, under Article 21(1a), inserted by Regulation (EU) 2025/2083.
For goods imported from 2027, pricing shifts to a weekly average under Article 21(1). The official 2026 prices are €75.36/tCO₂e for Q1, €75.28 for Q2 and €82.32 for Q3 (published October 5, 2026); the Q4 price is due on January 4, 2027.
The financial obligation in 2026 is reduced by the free allocation adjustment, but not to a fixed percentage of gross emissions. Certificates per tonne equal the embedded emissions minus the CBAM factor (97.5% in 2026) × the CBAM benchmark of the good.
For semi-finished steel from Türkiye (CN 7207 11 14) on default values, that is 2.541 tCO₂e (the 2.310 default plus the 10% mark-up) minus 0.975 × 1.364, leaving 1.2111 certificates per tonne, or €99.70 at the Q3 2026 price of €82.32.
Only a good exactly at its benchmark pays for 2.5% of its emissions; every tonne of CO₂e above the benchmark is charged in full.
The free allocation adjustment follows the SEFA methodology established in IR (EU) 2025/2620. The guide to the CBAM Regulation (EU) 2023/956 covers the legal architecture behind each of these obligations.
The definitive-phase rulebook received a mid-course correction on July 31, 2026, when Implementing Regulation (EU) 2026/1740 was published in the Official Journal, correcting the default values annexes with retroactive effect from January 1, 2026.
Importers who rely on default values for their 2026 embedded emissions apply the corrected figures for the full calendar year; the default values correction analysis covers the change.
Two weeks after that correction, on August 14, 2026, the European Commission published ten guidance documents covering the CBAM definitive period. The guidance documents are non-binding and sit outside the secondary legislation, but they arrive ahead of the first declaration cycle that concludes on September 30, 2027.
The Free Allocation Phase-Out: 2026 to 2034
The free allocation phase-out schedule is the mechanism that makes the CBAM timeline financially significant for the long term. As free ETS allocation is reduced, the deduction from each importer's certificate obligation shrinks. Costs are already material in 2026 for goods above their benchmark, and they rise fastest between 2029 and 2034.
The 9-year phase-out schedule below, established under Article 10a(1a) of EU ETS Directive 2003/87/EC as amended, shows the CBAM factor (the share of free allocation retained, which scales the deduction) and the share phased out in each year.
The cost column applies the legal method to semi-finished steel from Türkiye (CN 7207 11 14) on default values, at the official Q3 2026 price of €82.32 held constant.
| Year | CBAM Factor | Free Allocation Phased Out | Cost per Tonne (Türkiye, CN 7207 11 14, Default Values, €82.32/tCO₂e) |
|---|---|---|---|
| 2026 | 97.5% | 2.5% | €99.70 |
| 2027 | 95% | 5% | €121.52 |
| 2028 | 90% | 10% | €146.15 |
| 2029 | 77.5% | 22.5% | €160.19 |
| 2030 | 51.5% | 48.5% | €189.38 |
| 2031 | 39% | 61% | No figure: no correction factor set |
| 2032 | 26.5% | 73.5% | No figure: no correction factor set |
| 2033 | 14% | 86% | No figure: no correction factor set |
| 2034 | No CBAM factor applies | 100% | €247.21 |
Inputs: default value 2.310 tCO₂e per tonne; mark-up 10% for 2026, 20% for 2027 and 30% from 2028; default benchmark 1.364 (BF/BOF route); cross-sectoral correction factor 100% for 2026 to 2030. From 2034 no deduction applies, so the cost is the default with mark-up multiplied by the price. The benchmarks may be updated for goods imported from 2027 (recital 10 of IR (EU) 2025/2620), so the figures after 2026 may change.
The steepest step in this CBAM timeline occurs between 2029 and 2030, when the CBAM factor falls from 77.5% to 51.5%. Importers planning supply chain decarbonization or supplier switching decisions need to model their exposure across this 2029 to 2030 cliff, not just their 2026 starting position.
Proposal note: on July 17, 2026, the European Commission published COM(2026) 616, its proposal for the next EU ETS revision.
If adopted, it would reintroduce 15% of the phased-out free allocation for CBAM sectors from 2028 and extend the phase-out endpoint from 2034 to 2038. The proposed CBAM factors are shown below beside the law in force; nothing would change for 2026 and 2027.
| Year | CBAM factor, law in force | CBAM factor, COM(2026) 616 (proposal, not law) |
|---|---|---|
| 2026 | 97.5% | 97.5% |
| 2027 | 95% | 95% |
| 2028 | 90% | 91.5% |
| 2029 | 77.5% | 81% |
| 2030 | 51.5% | 59% |
| 2031 | 39% | 48% |
| 2032 | 26.5% | 37.5% |
| 2033 | 14% | 27% |
| 2034 to 2037 | No factor applies | 15% |
| From 2038 | No factor applies | 0% |
Sources: Article 10a(1a) of Directive 2003/87/EC; Article 1(15)(b)(i) of COM(2026) 616.
This is a legislative proposal, not adopted law. EU environment ministers held a policy debate on it on October 12, 2026 and decided nothing, and the Irish Presidency of the Council aims at a general approach in December 2026.
As of October 13, 2026 the 2026 to 2034 schedule remains the binding timeline, and this site has calculated no costs on the proposed factors. See the report on the October 12 debate and the EU ETS Phase 5 revision proposal analysis.
Certificate price alerts and the regulatory changes that matter. Get weekly updates on what happens regarding anything CBAM-related. No spam, unsubscribe anytime.
We store only your email address for these alerts. Privacy policy
What Changed After the Omnibus Amendment?
The October 2025 Omnibus amendment (Regulation (EU) 2025/2083, adopted October 8, 2025, published October 17, 2025, in force October 20, 2025) revised the CBAM timeline in 5 material respects. The CBAM omnibus article details all changes; the timeline-specific changes are listed below.
The 5 timeline changes introduced by Regulation (EU) 2025/2083 are as follows.
- Declaration deadline extended: from May 31 to September 30 of the year following the import year (Article 6, as amended). The first declaration covering 2026 imports is due September 30, 2027, not May 31, 2027.
- Certificate sales start delayed: from January 1, 2026 to February 1, 2027 (Article 20(1)), via a Common Central Platform managed by the European Commission.
- Quarterly holding requirement reduced: from 80% to 50% of the embedded emissions in goods imported since the start of the calendar year, applicable from 2027 with the free allocation adjustment taken into account (Article 22(2), as amended). No holding applies to 2026 imports.
- Verifier registration date fixed: September 1, 2026 as the earliest date accredited verifiers can request registration in the CBAM Registry under Article 10a(1).
- De minimis threshold introduced: importers whose CBAM goods do not exceed 50 tonnes of net mass in a calendar year (per importer, across all CN codes and origins, excluding electricity and hydrogen) are exempt under Article 2a, inserted by Regulation (EU) 2025/2083, and declare the exemption in the customs declaration.
Certificate Deadlines: Surrender, Buyback, and Cancellation
Three annual CBAM certificate deadlines operate after the first declaration year, each falling in a defined window. The CBAM declaration page covers the full submission process; the calendar below shows the three certificate lifecycle deadlines.
The 3 certificate deadlines that follow each declaration year are structured as follows.
- September 30: The annual CBAM declaration deadline. Authorized declarants submit their declaration and surrender the certificates that correspond to the embedded emissions of goods imported in the preceding calendar year, after the free allocation adjustment and any Article 9 reduction.
- October 31: The buyback deadline. Declarants may ask for excess certificates to be repurchased at the original purchase price, limited under Article 23(2) to the number of certificates they had to purchase under Article 22(2) in the calendar year of purchase.
- November 1: Certificate cancellation date. Certificates purchased during the year before the previous calendar year that remain on the account are cancelled without compensation (Article 24(1)); on November 1, 2027 the certificates purchased for 2026 emissions are cancelled (Article 24(2)).
The first cycle of these 3 deadlines activates in autumn 2027: declaration due September 30, buyback deadline October 31, cancellation November 1. For 2026, CBAM certificates purchased via the Common Central Platform from February 1, 2027 onward are the instruments used for that surrender.
The CBAM certificates page covers the certificate purchase mechanics ahead of that February 1, 2027 sales date.
Consultation note: the detailed rules for certificate sales and repurchase are still in draft. The European Commission's consultation on the draft delegated regulation (Article 20(6)) closed on August 6, 2026, drawing 93 submissions; adoption remains planned for Q4 2026. The deadlines above are set by Regulation (EU) 2025/2083.
Institutional Dates to Watch in Autumn 2026
Eight institutional dates and stated targets sit outside the binding EU compliance calendar but are worth tracking, as of October 23, 2026.
- September 7, 2026: A "European Convoy for Industrial Competitiveness," staged by a steel coalition of roughly 500 signatories urging the extension of CBAM to downstream products, was scheduled to arrive in Brussels one week before the September 15 plenary vote on the downstream mandate. This is a context event announced by the coalition, not a legislative step; the steel coalition's Brussels convoy report covers the campaign.
- September 15, 2026: The European Parliament adopted its first-reading negotiating mandate on the proposed downstream scope expansion (COM(2025)989) by 464 votes to 50 with 159 abstentions, opening the way for trilogues with the Council, which the institutions aim to conclude before the end of 2026.
- September 18, 2026: Submission deadline in Australia's review of its Safeguard Mechanism, which opened on August 7, 2026.
- September 24, 2026: The Council's Ad Hoc Working Party on the Carbon Border Adjustment Mechanism was scheduled to meet, per the Consilium meeting register.
- September 25, 2026: The WTO Dispute Settlement Body established a panel in dispute DS639 on Russia's second request, the first WTO panel on a carbon border measure.
- October 20, 2026: First trilogue on the downstream file, held without an overall agreement according to press reports.
- November 30, 2026 (reported): Second trilogue on the downstream file.
- End of 2026 (stated targets): The Irish Presidency of the Council aims to reach a general approach on the EU ETS revision proposal COM(2026) 616 at the December Environment Council, according to its paper of September 25, 2026; ministers held a policy debate on October 12, 2026 and decided nothing. Parliament's rapporteur Liese has set the same horizon: positions by the end of 2026 and trilogues from January 2027 (Brussels Morning, around August 20, 2026). These are stated targets, not an adopted schedule; see the report on the October 12 debate and the Liese trilogue target report.
CBAM Timeline: Contextual Border with Key Compliance Actions
The CBAM implementation timeline contains 4 compliance actions that require preparation well before their stated deadlines. Understanding these lead times is the operational difference between compliance and penalty exposure.
The 4 preparation-critical CBAM deadlines with their required lead times are listed below.
- March 31, 2026 authorization deadline: Requires a complete application (customs compliance history, tax registration, company documents) submitted to the national competent authority. The 120-day decision window under Article 4(1) of IR 2025/486 means applications must be complete, not just submitted.
- September 1, 2026 verifier registration: Since September 1, 2026, accredited verifiers can request registration in the CBAM Registry (Article 10a(1)). Verifiers are accredited by a national accreditation body of an EU member state under DR (EU) 2025/2551, against EN ISO/IEC 17029:2019. As of November 12, 2026, seven verification bodies were documented as accredited by five national accreditation bodies (ESYD in Greece, Accredia in Italy, Swedac in Sweden, RvA in the Netherlands and BELAC in Belgium), and the Commission's list of accredited verifiers was still unpublished. Importers that will declare actual values for 2026 need a verifier under contract well before the declaration deadline.
- February 1, 2027 certificate sales start: Importers need CBAM Registry accounts active, authorized declarant status confirmed, and a forecast of their 2026 embedded emissions calculated before this date to begin purchasing certificates. The CBAM authorized declarant page covers the authorization requirements ahead of this window.
- September 30, 2027 first declaration: The declaration covers every CBAM good imported during calendar year 2026, on actual emissions or default values, with certificates surrendered for the emissions that remain after the free allocation adjustment. Verification is required only where actual emissions are declared (Article 8(1)), and IR (EU) 2025/2546 requires a physical site visit in the first year an installation is verified.
Is the CBAM Scope Expanding After 2026?
A proposal to that effect is in negotiation, and nothing has been adopted. The European Commission published a formal legislative proposal (COM(2025)989) on December 17, 2025, proposing to expand the CBAM scope to approximately 180 downstream steel- and aluminium-intensive products from January 1, 2028. The proposal's annex lists, among others, vehicle parts, machinery, electric motors, and household washing machines. This expansion requires approval by both the European Parliament and the Council under the ordinary legislative procedure.
As of October 23, 2026, both co-legislators have adopted their negotiating positions: the Council's general approach, adopted June 12, 2026, adds about 200 codes per Mayer Brown (just over 300 entries and codes in total by cbamguide.com's count), while the European Parliament's ENVI committee adopted its position on July 6, 2026 (56-11-12), with a list that trade press puts at about 457 downstream products and tighter anti-circumvention rules.
Parliament's plenary adopted its first-reading negotiating mandate on September 15, 2026, by 464 votes to 50 with 159 abstentions. The first trilogue on October 20, 2026 ended without an overall agreement, according to press reports, and a second is reported for November 30, 2026; a final deal is targeted before the end of 2026 so the expansion can still take effect from January 1, 2028. The current CBAM scope (6 sectors) remains unchanged until co-legislators reach and adopt a final agreement. For the full side-by-side comparison of the three institutions' product lists, see the CBAM downstream expansion tracker.
Does the CBAM Timeline Apply to All Third Countries?
No. Goods originating in Iceland, Liechtenstein, Norway, and Switzerland are exempt from CBAM obligations under Article 2(4) and Annex III, point 1 of Regulation (EU) 2023/956, as are goods from the territories of Büsingen, Heligoland, Livigno, Ceuta and Melilla. Under Article 2(6), these are origins where the EU ETS applies or whose emissions trading system is fully linked to it. The CBAM timeline applies to imports from all other third countries, including countries with their own carbon pricing schemes. Article 9 allows a reduction for a carbon price effectively paid in a third country, but as of October 12, 2026 its implementing act was still a draft and no country's carbon price had been recognised.
When Does the Quarterly Holding Requirement Apply?
The quarterly holding requirement applies from 2027, not from the start of the definitive phase. Under Article 22(2) as amended by Regulation (EU) 2025/2083, authorized declarants must hold CBAM certificates equal to at least 50% of the embedded emissions in goods imported since the start of the calendar year, assessed at the end of each quarter (March 31, June 30, September 30, December 31). Those emissions are determined on default values without the mark-up or on the certificates surrendered for the preceding year, and the free allocation adjustment is taken into account. The first check falls on March 31, 2027, and no holding applies to goods imported in 2026.
A shortfall does not trigger the Article 26(1) penalty directly. Under Article 22(3), the competent authority notifies the declarant, who has one month to bring the account up to the required number. The Article 26(1) penalty applies to certificates not surrendered by the September 30 deadline.
Does the CBAM Timeline Align with the UK CBAM?
No. The UK CBAM starts January 1, 2027, one year after the EU CBAM definitive phase, and uses a tax-based mechanism rather than a certificate system. The UK mechanism has different sector coverage, different price calculation methods, and different filing deadlines. The UK calendar, from the January 1, 2027 start to the first return on May 31, 2028 and the quarterly returns that follow, is set out on the UK CBAM deadlines page. The UK legal framework is substantially complete: Part 5 of the Finance Act 2026 and five statutory instruments made in July and September 2026 take effect on January 1, 2027; the House of Commons approved SI 2026/809 on October 14, 2026.
Goods traded across the UK-EU corridor may face compliance obligations under both mechanisms, and as of October 12, 2026 the risk of double-payment for UK-EU trade remains unresolved. Formal UK-EU talks on linking the two emissions trading systems have been underway since January 2026. POLITICO reported on October 7, 2026 that an agreement had been reached. On October 12, 2026 the Prime Minister told the House of Commons that the UK-EU summit takes place in Brussels on November 20, 2026 with "a deal on emissions trading" on the table; he announced no agreement, and an exemption for UK-origin goods would apply only once a link is in force.
Could Russia's WTO Challenge Change the CBAM Timeline?
No. As of October 12, 2026, no date in the CBAM timeline has moved because of WTO proceedings. Russia is challenging CBAM at the World Trade Organization in dispute DS639. At the Dispute Settlement Body (DSB) meeting on July 24, 2026, the EU blocked Russia's first request for a dispute panel, and on September 25, 2026 the DSB established the panel on Russia's second request. A panel report is realistic in 2027 to 2028. Every deadline on this page applies in full while the dispute proceeds.