EU ETS free allocation for CBAM goods is phased out between 2026 and 2034: EU producers keep 97.5% of it in 2026 and none from 2034. The legal CBAM factor is that retained share, set in Article 10a(1a) of Directive 2003/87/EC.
It falls in eight steps (97.5%, 95%, 90%, 77.5%, 51.5%, 39%, 26.5%, 14%), and no CBAM factor applies from 2034. The steepest drop comes between 2029 and 2030, from 77.5% to 51.5%.
Understanding this schedule is the foundation of any multi-year CBAM compliance strategy, because the deduction it gives importers shrinks every year while the default-value mark-up rises.
What is the link between free allocation and CBAM? Free allocation and CBAM are directly coupled by design. As long as EU domestic producers receive EU ETS allowances at no charge, the EU carbon border adjustment mechanism deducts a free allocation adjustment from the certificates an importer owes (Article 31 of Regulation (EU) 2023/956).
The adjustment per tonne of good is the CBAM factor × the cross-sectoral correction factor × the CBAM benchmark of the good. It is a benchmark-based quantity, not a percentage of the importer's own emissions.
Two percentages must be kept apart. The CBAM factor is the share of free allocation retained: 97.5% in 2026. The share phased out is its complement: 2.5% in 2026 and 100% from 2034.
Only a good whose embedded emissions equal its benchmark pays for 2.5% of its emissions in 2026. Every tonne of CO₂e above the benchmark, including the whole default-value mark-up, is charged at the full certificate price.
This article presents the complete phase-out schedule, year-by-year net cost examples for steel imported on default values, and the planning implications for importers who must build this cost curve into procurement and supply chain decisions made today.
Proposed Change: COM(2026) 616 Would Slow the Phase-Out and Extend It to 2038
On July 17, 2026, the European Commission published COM(2026) 616, the ETS Phase 5 revision proposal, which would slow the free allocation phase-out described on this page.
The proposal would reintroduce 15% of the phased-out free allocation for CBAM sectors from 2028 and extend the phase-out endpoint from 2034 to 2038, explicitly slowing the CBAM phase-in as a consequence. Our full analysis of the proposal and its CBAM implications is available in EU ETS Phase 5 revision slows the CBAM phase-in.
The proposal would rewrite the CBAM factor from 2028. The table sets the proposed values beside the law in force; nothing would change for 2026 and 2027.
| Year | CBAM factor, law in force | CBAM factor, COM(2026) 616 (proposal, not law) |
|---|---|---|
| 2026 | 97.5% | 97.5% |
| 2027 | 95% | 95% |
| 2028 | 90% | 91.5% |
| 2029 | 77.5% | 81% |
| 2030 | 51.5% | 59% |
| 2031 | 39% | 48% |
| 2032 | 26.5% | 37.5% |
| 2033 | 14% | 27% |
| 2034 to 2037 | No factor applies | 15% |
| From 2038 | No factor applies | 0% |
Sources: Article 10a(1a) of Directive 2003/87/EC; Article 1(15)(b)(i) of COM(2026) 616.
COM(2026) 616 is a proposal, not adopted law. EU environment ministers held a policy debate on it on October 12, 2026 without taking a decision, and the Irish Presidency of the Council aims at a general approach, the Council's negotiating position, at the December Environment Council.
The report on the debate has the state of play. Council and Parliament can change every proposed figure.
As of October 13, 2026 the 2026 to 2034 schedule in Article 10a(1a) of Directive 2003/87/EC remains the binding law, and every table and cost figure on this page reflects that current schedule. Importers should treat the proposal as a planning scenario; this site has not calculated costs on the proposed factors.
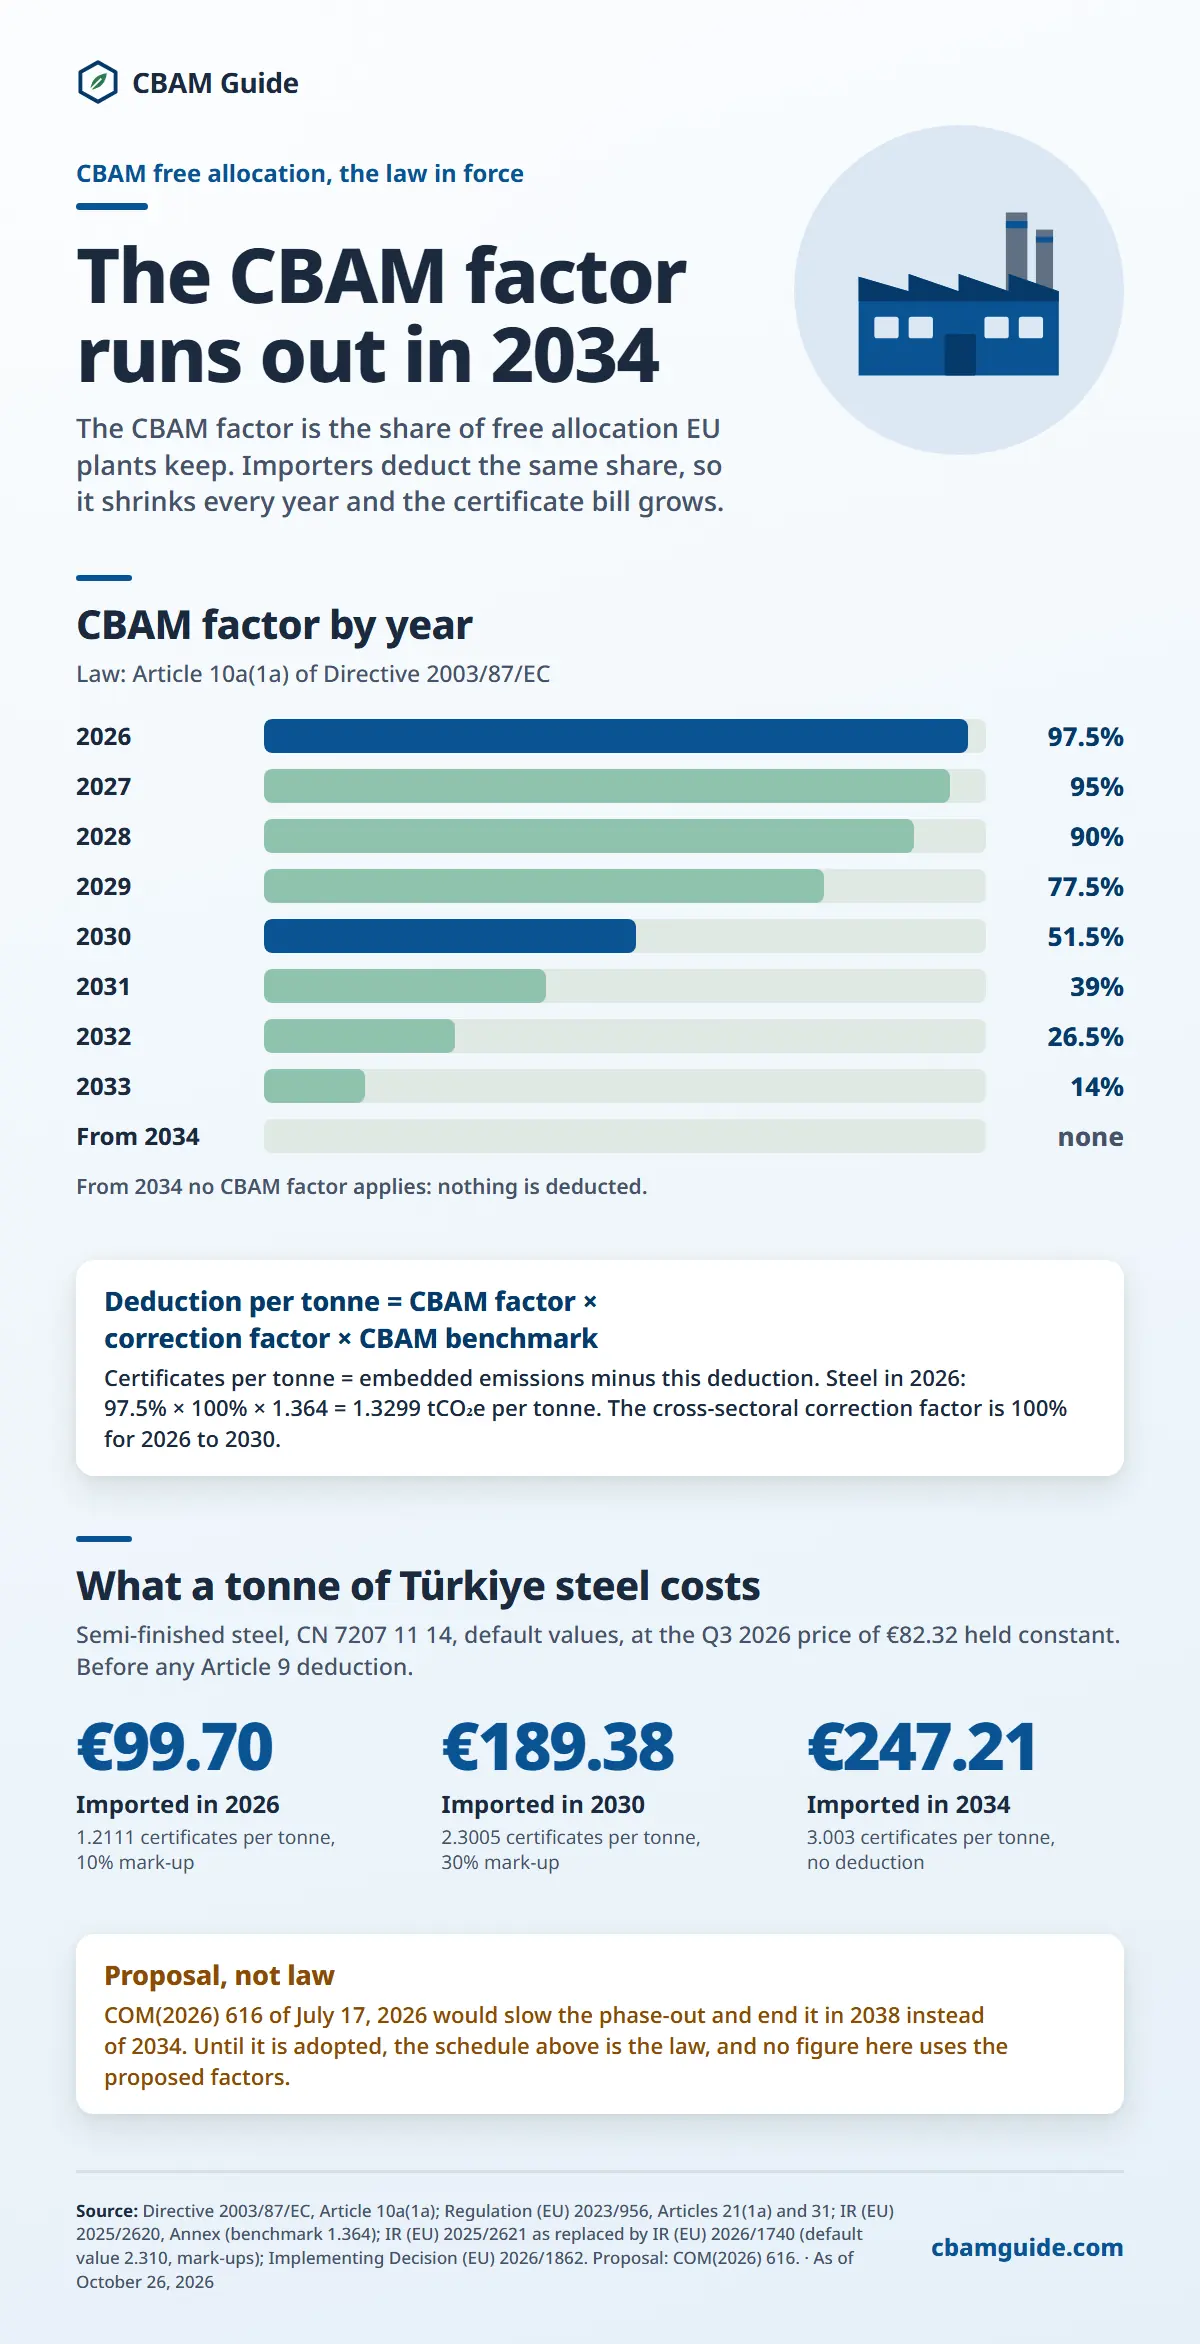
Text version of this infographic
CBAM factor by year
Law: Article 10a(1a) of Directive 2003/87/EC
- 2026: 97.5%
- 2027: 95%
- 2028: 90%
- 2029: 77.5%
- 2030: 51.5%
- 2031: 39%
- 2032: 26.5%
- 2033: 14%
- From 2034: none
From 2034 no CBAM factor applies: nothing is deducted.
Deduction per tonne = CBAM factor × correction factor × CBAM benchmark: Certificates per tonne = embedded emissions minus this deduction. Steel in 2026: 97.5% × 100% × 1.364 = 1.3299 tCO₂e per tonne. The cross-sectoral correction factor is 100% for 2026 to 2030.
What a tonne of Türkiye steel costs
Semi-finished steel, CN 7207 11 14, default values, at the Q3 2026 price of €82.32 held constant. Before any Article 9 deduction.
- €99.70: Imported in 2026 (1.2111 certificates per tonne, 10% mark-up)
- €189.38: Imported in 2030 (2.3005 certificates per tonne, 30% mark-up)
- €247.21: Imported in 2034 (3.003 certificates per tonne, no deduction)
Proposal, not law: COM(2026) 616 of July 17, 2026 would slow the phase-out and end it in 2038 instead of 2034. Until it is adopted, the schedule above is the law, and no figure here uses the proposed factors.
What Is EU ETS Free Allocation and Why Does It Phase Out?
EU ETS free allocation is the provision of EU Emissions Trading System allowances to domestic EU producers at no charge, established under Article 10a of Directive 2003/87/EC to protect energy-intensive industries from carbon leakage before a global carbon pricing system existed.
Free allocation historically shielded EU steelmakers, cement producers, aluminium smelters, and fertilizer manufacturers from the full cost of EU ETS compliance, preventing them from being undercut by competitors in countries with no carbon price.
Free allocation creates an asymmetry. A Chinese steelmaker exporting to the EU pays no carbon price at all, while a competing EU producer pays a reduced ETS cost (after free allocation reduces the net liability).
The gap is smaller than full ETS exposure but still represents a competitive disadvantage for EU producers compared to non-EU producers with zero carbon costs.
CBAM is the mechanism designed to close this gap by applying a carbon cost to imports. Free allocation phases out in parallel with CBAM phasing in, so the two mechanisms maintain a consistent competitive signal throughout the transition.
The legal mandate for the phase-out comes from Article 10a(1a) of Directive 2003/87/EC as amended, which ties the free allocation reduction schedule directly to the CBAM regulation entering its definitive phase on January 1, 2026.
Under the law in force, the phase-out is not discretionary: it is legally fixed for every year of the schedule. The COM(2026) 616 proposal of July 17, 2026 would change that schedule from 2028 onward if adopted, as covered above, but it remains a proposal in co-decision and does not alter the current legal position.
Complete EU ETS Free Allocation Phase-Out Schedule 2026–2034
The phase-out schedule, codified in Article 10a(1a) of Directive 2003/87/EC, sets a precise CBAM factor for each calendar year from 2026 to 2033.
The table below shows the CBAM factor, the share of free allocation phased out, and the net CBAM cost per tonne for one verified example: semi-finished steel from Türkiye (CN 7207 11 14) imported on default values, at the official Q3 2026 certificate price of €82.32 per tonne of CO₂e (published October 5, 2026).
The net cost follows the legal formula: certificates = max[0; specific embedded emissions minus the free allocation adjustment minus the Article 9 carbon price term] × mass (Articles 6(2)(c) and 31 of Regulation (EU) 2023/956; Implementing Regulation (EU) 2025/2620).
For 2026 the default value is 2.310 tCO₂e per tonne (Annex I to IR (EU) 2025/2621 as replaced by IR (EU) 2026/1740), or 2.541 with the 10% mark-up. The adjustment is 0.975 × 1.00 × the default benchmark of 1.364, which is 1.3299. That leaves 1.2111 certificates per tonne, or €99.70.
| Year | CBAM Factor (free allocation retained) | Share of Free Allocation Phased Out | Net CBAM Cost: Türkiye Steel Billets on Default Values (€82.32) |
|---|---|---|---|
| 2025 | 100% | 0% | No certificates (transitional period) |
| 2026 | 97.5% | 2.5% | €99.70/t |
| 2027 | 95% | 5% | €121.52/t |
| 2028 | 90% | 10% | €146.15/t |
| 2029 | 77.5% | 22.5% | €160.19/t |
| 2030 | 51.5% | 48.5% | €189.38/t |
| 2031 | 39% | 61% | Not yet calculable |
| 2032 | 26.5% | 73.5% | Not yet calculable |
| 2033 | 14% | 86% | Not yet calculable |
| 2034 | No CBAM factor applies | 100% | €247.21/t |
Source: Article 10a(1a), Directive 2003/87/EC as amended. Inputs: default value 2.310 with a mark-up of 10% (2026), 20% (2027) and 30% (from 2028); default benchmark 1.364 (IR (EU) 2025/2620, Annex, point 5.3, Column B, route (C)); cross-sectoral correction factor 100% for 2026 to 2030 (Implementing Decision (EU) 2026/1862).
The certificate price and the benchmark are held constant at €82.32 and 1.364, although updated benchmarks are foreseen for goods imported from 2027. No correction factor is set for 2031 to 2033. For 2034 the adjustment is zero, so the cost is the default with mark-up (3.003) × the price.
The 2026 net cost of €99.70 per tonne is 47.7% of the gross figure of €209.18 (2.541 × €82.32), not 2.5% of it. The 2034 figure of €247.21 per tonne (at the Q3 2026 price) is about 2.5 times the 2026 cost.
Companies that treat 2026 as a "low-cost year" misread the mechanism: the cost is material from the first year and rises in every later year, with the largest step in the CBAM factor at the 2029-to-2030 transition.
How the CBAM Factor Interacts with Certificate Obligations
The CBAM factor reduces the number of CBAM certificates an authorized declarant must surrender, but it does so through the benchmark.
Under the SEFA methodology established by Implementing Regulation (EU) 2025/2620, the specific embedded free allocation is the CBAM factor × the cross-sectoral correction factor × the CBAM benchmark, and it is subtracted from the embedded emissions of the imported goods.
The deduction exists only because competing EU producers still receive free ETS allowances at benchmark level.
This coupling has a specific consequence: as EU domestic producers see their free allocation shrink each year, their own carbon cost increases. CBAM tracks that increase by lowering the CBAM factor in parallel, which shrinks the importer's deduction.
The competitive relationship between EU producers and non-EU exporters therefore remains approximately stable throughout the phase-out, which is the stated policy objective. What changes is the absolute cost level for all parties.
The SEFA calculation is applied at benchmark level. The reduction is tied to the CBAM benchmark listed for each CN code in point 5.3 of the Annex to IR (EU) 2025/2620, not to the free allocation received by any specific EU producer and not to the importer's own emissions.
Importers cannot calculate their reduction on the basis of which EU company they are "competing with." On default values the Column B default benchmark applies, for the production route printed in the country's Annex I row. On actual values the Column A process benchmark applies, plus the adjustment embedded in precursors.
How does the CBAM factor affect multi-year contract pricing? Contracts signed in 2026 at import prices that assume the 2026 CBAM cost will be structurally underpriced by 2029.
A three-year supply contract for Turkish steel billets (CN 7207 11 14, default values) that prices in the 2026 cost of €99.70 per tonne faces €160.19 per tonne in 2029 at the same certificate price, because the mark-up rises to 30% and the CBAM factor falls to 77.5%.
Procurement teams must model the full phase-out schedule into any contract with a term extending beyond 24 months.
Net Cost Impact by Sector: 2026 vs 2030 vs 2034
The free allocation phase-out affects CBAM goods differently depending on how far their embedded emissions sit above their benchmark.
The goods covered by Regulation (EU) 2023/956 carry very different default values and benchmarks, so the absolute cost escalation varies even though the CBAM factor schedule is identical for every good that has a benchmark. Electricity has no free allocation adjustment at all (Article 1(2) of IR (EU) 2025/2620).
The table below compares net CBAM costs per tonne at three key milestones in the phase-out for six goods imported on default values, using the official Q3 2026 certificate price of €82.32 per tonne of CO₂e.
To run the same calculation on your own CN codes and volumes across the full 2026 to 2034 curve, use the CBAM cost calculator.
| Origin and Product (CN code) | Default Value / Default Benchmark (tCO₂e/t) | Net Cost 2026 (CBAM factor 97.5%) | Net Cost 2030 (CBAM factor 51.5%) | Net Cost 2034 (no CBAM factor) |
|---|---|---|---|---|
| Türkiye, semi-finished steel (7207 11 14) | 2.310 / 1.364 | €99.70/t | €189.38/t | €247.21/t |
| South Korea, hot-rolled flat steel (7208) | 2.118 / 1.370 | €81.83/t | €168.58/t | €226.66/t |
| "Other countries", grey Portland cement (2523 29 00) | 1.440 / 0.666 | €76.94/t | €125.87/t | €154.10/t |
| China, unwrought aluminium (7601) | 3.000 / 1.423 | €157.44/t | €260.72/t | €321.05/t |
| Egypt, urea (3102 10 19) | 1.390 / 0.902 | €43.17/t | €77.33/t | €115.57/t |
| "Other countries", hydrogen (2804 10 00) | 17.740 / 5.089 | €1,197.94/t | €1,682.72/t | €1,898.46/t |
Default values are the total-emissions figures in Annex I to IR (EU) 2025/2621 as replaced by IR (EU) 2026/1740. Benchmarks are Column B of point 5.3 of the Annex to IR (EU) 2025/2620, on the route the country row indicates: (C), blast furnace, for the two steel rows and (K), primary, for aluminium. The mark-up is 10% in 2026 and 30% from 2028 (urea: 1% in every year). "Other countries" is the Annex I table for origins without their own row.
The price and the benchmarks are held constant. The 2034 cost is the default with mark-up × the price, because the adjustment is zero. All costs are before any Article 9 reduction for carbon prices paid in the country of origin, and they fluctuate with the certificate price.
Hydrogen stands apart from other CBAM goods because its default value sits far above its benchmark. The "Other countries" default of 17.740 tCO₂e per tonne is more than seven times the Türkiye billet default, against a benchmark of 5.089.
At the Q3 2026 price, hydrogen imported on that default costs €1,197.94 per tonne in 2026 and €1,898.46 per tonne in 2034.
These figures rise proportionally with the certificate price. In a sensitivity case at €126 per tonne of CO₂e, a price this site uses as a 2030 planning scenario and not a forecast, the 2030 obligation of 20.44 certificates per tonne would cost €2,575.59.
Certificate price alerts and the regulatory changes that matter. Get weekly updates on what happens regarding anything CBAM-related. No spam, unsubscribe anytime.
We store only your email address for these alerts. Privacy policy
The 2029–2030 Free Allocation Cliff: Why It Requires Early Planning
The 2029-to-2030 transition is the steepest single-year step in the entire phase-out schedule. The CBAM factor falls from 77.5% to 51.5%, so the share of free allocation phased out more than doubles in one year, from 22.5% to 48.5%.
For Turkish steel billets on default values (CN 7207 11 14), this adds €29.19 per tonne in a single calendar year (from €160.19 to €189.38 at €82.32).
For unwrought aluminium from China (CN 7601), the step is €30.46 per tonne (from €230.26 to €260.72). The step applies in the same year to every CBAM good that has a benchmark.
Three planning implications follow from the 2029-to-2030 cliff:
- Supply chain decarbonization decisions that require 3 to 5 years to implement (switching to low-carbon steel suppliers, negotiating verified emission data from producers, investing in production process changes) need to begin no later than 2026 to take effect before 2030.
- Financial forecasting models that use 2026 or 2027 CBAM costs as the "run rate" will systematically underestimate 2030 and beyond. The correct approach is to model every year of the schedule with the legal formula, using a range of ETS price scenarios.
- Companies importing from countries with their own emissions trading systems, such as South Korea's K-ETS or China's national ETS, may be able to claim an Article 9 reduction for a carbon price effectively paid. As of October 12, 2026 the implementing act is still a draft and no country's carbon price has been recognised, so cost models should not assume a deduction.
The 2026-to-2029 period provides a window during which compliance processes can be built, suppliers can be qualified, verification arrangements can be established, and contract structures can be renegotiated. Companies that use this window strategically reach 2030 with lower exposure than those who treat the early years as negligible.
How Free Allocation Phase-Out Affects EU Domestic Producers
EU domestic producers in CBAM sectors face the same schedule from the other side: their free allocation is multiplied by the falling CBAM factor.
An EU steelmaker entitled to, for example, 1,000 free ETS allowances at a CBAM factor of 100% receives only 975 in 2026 (a 2.5% reduction), 950 in 2027, and 0 in 2034, other things being equal. This means EU producers face rising carbon costs in absolute terms, independent of what happens to CBAM for importers.
The intended outcome is a level playing field at the margin: as EU producer costs rise due to free allocation reduction, non-EU exporter costs rise in parallel through increasing CBAM certificate obligations. Neither side receives a structural advantage through the transition. A separate issue sits outside that design: the reverse carbon leakage problem.
Reverse carbon leakage occurs when EU producers export to non-EU markets. An EU steelmaker exporting to Japan or South Korea competes against local producers who pay no equivalent carbon price, while the EU producer's ETS costs rise as free allocation decreases. CBAM provides no rebate or compensation for this export exposure.
The Temporary Decarbonisation Fund proposed in COM(2025)990 of December 17, 2025 would support EU producers of listed aluminium, fertiliser and iron and steel goods that stay exposed to carbon leakage, using 25% of Member States' CBAM certificate revenue for 2026 and 2027, with support paid in 2028 and 2029 for goods produced in 2026 and 2027. The proposal never mentions exports, so it is not an export rebate.
Parliament adopted its amendments in plenary on September 15, 2026, by 433 votes to 97, with 146 abstentions (procedure 2025/0418(COD), rapporteur Pascal Canfin).
They would extend the support window to 2027-to-2029, add urea, ammonium nitrate and ammonium sulphate to the fertiliser goods on the Commission's list, open the fund to downstream operators that use CBAM-covered goods as inputs, and redirect unused revenue to EU international climate finance.
The fund remains a proposal as of October 12, 2026: it still has to be agreed with the Council.
CBAM Free Allocation and the SEFA Methodology
The reduction in CBAM certificate obligations is calculated through the SEFA (Specific Embedded Free Allocation) methodology established in Implementing Regulation (EU) 2025/2620. SEFA converts the CBAM factor percentage into a concrete deduction, in tCO₂e per tonne, for each good.
The methodology uses CBAM benchmarks that mirror the free allocation EU producers receive at benchmark level. They are listed per CN code in point 5.3 of the Annex to IR (EU) 2025/2620.
The deduction for any import is calculated as follows: SEFA = CBAM factor × cross-sectoral correction factor × CBAM benchmark, and SEFA is subtracted from the specific embedded emissions of the good.
The cross-sectoral correction factor is 100% for each year from 2026 to 2030 (Implementing Decision (EU) 2026/1862). This approach ensures that the CBAM cost on imports reflects the net ETS cost on equivalent EU domestic production, not a theoretical gross cost.
The SEFA methodology matters for three reasons. First, it confirms that CBAM is not a simple carbon tariff on gross emissions. It is a net adjustment calibrated to domestic competitive conditions.
Second, the deduction is fixed per tonne of good and does not grow with the emissions declared, so the default-value mark-up and every tonne of CO₂e above the benchmark are charged in full.
Third, the deduction changes between years: the CBAM factor falls, and recital 10 of IR (EU) 2025/2620 foresees updated benchmarks for goods imported from January 1, 2027.
How Free Allocation Reduction Connects to CBAM Compliance Planning
Does free allocation phase-out change what importers must do in 2026?
The free allocation phase-out changes the financial scale of CBAM obligations but does not change the compliance steps required. Importers above the 50-tonne threshold must hold authorized CBAM declarant status, determine the embedded emissions of their imports from verified actual values or from default values, and surrender certificates by September 30 of the following year. Verification by an accredited verifier is required only where actual values are used (Article 8(1)), and the quarterly holding rule of Article 22(2) applies from 2027. The CBAM factor determines the size of the deduction, but the process is identical whether the factor is 97.5% or no factor applies.
Is the 2026 CBAM cost small because 97.5% of free allocation is retained?
No. The 97.5% applies to the benchmark, not to the importer's emissions. For a mid-size importer bringing in 10,000 tonnes of Turkish steel billets (CN 7207 11 14) on default values, the 2026 obligation is 12,111 certificates (10,000 t × 1.2111), or approximately €997,000 at the official Q3 2026 price of €82.32. For 2030 imports of the same volume it is approximately €1.89 million at the same price and benchmark.
Building the data flows, supplier relationships, and verification processes in 2026 still pays off. Verified actual values replace the marked-up default in every later year. Importers should model both paths, because the actual-value path uses a different benchmark basis.
What happens if a company does not obtain authorized declarant status?
An importer who brings CBAM goods into the EU without authorization faces a penalty of three to five times the penalty of Article 26(1), for each certificate not surrendered, under Article 26(2) of Regulation (EU) 2023/956 as amended by Regulation (EU) 2025/2083. The Article 26(1) penalty is the EU ETS excess emissions penalty of €100 per tonne of CO₂e before indexation, so the range is €300 to €500 per certificate before indexation.
For 10,000 tonnes of Turkish steel billets imported in 2026 on default values (12,111 certificates), that is approximately €3.63 million to €6.06 million before indexation, compared to a certificate cost of approximately €997,000. For an importer without the status that exceeds the 50-tonne threshold, payment of the penalty releases it from the declaration and surrender obligations for those imports (Article 26(2a)).
Free Allocation Phase-Out Across the CBAM Regulatory Framework
The free allocation phase-out is one component within the broader CBAM regulatory architecture. The CBAM regulation (Regulation (EU) 2023/956 as amended by Regulation (EU) 2025/2083) links the certificate obligation directly to the ETS Directive: Article 31 of the Regulation requires the free allocation adjustment, and Article 10a(1a) of Directive 2003/87/EC sets the CBAM factor.
This legal coupling means that a change to the phase-out timeline is made by amending that provision of the Directive, as COM(2026) 616 proposes, and the CBAM adjustment then follows it.
The EU ETS and CBAM certificate prices are directly connected through this architecture. CBAM certificate prices are set as the quarterly average of EU ETS auction closing prices for goods imported in 2026 (Article 21(1a)) and as the weekly average from 2027 onward (Article 21(1)), with the calculation and publication rules in Implementing Regulation (EU) 2025/2548.
This means that ETS price volatility transmits directly to CBAM certificate costs. A certificate price of €100 per tonne in 2030 would raise the net cost of the Turkish billet example to €230.05 per tonne, compared to €189.38 at €82.32.
How Are Embedded Emissions Calculated for CBAM Certificate Purposes?
Understanding how embedded emissions are calculated is necessary before any free allocation cost model can be built. The embedded emissions figure used to calculate CBAM certificate obligations comes from one of two sources: verified actual emissions from the production installation, or default values published in Implementing Regulation (EU) 2025/2621, as corrected by IR (EU) 2026/1740. Default values carry a mark-up of 10% on the total-emissions value in 2026, rising to 20% in 2027 and 30% from 2028 onward (1% for fertilizers in every year), making them progressively more expensive relative to actual emissions data as the phase-out advances.
Does Free Allocation Phase-Out Apply Equally to All CBAM Sectors?
The CBAM factor schedule applies uniformly to every CBAM good that has a benchmark: iron and steel, cement, aluminium, fertilizers, and hydrogen. Electricity is the exception: its free allocation adjustment is zero (Article 1(2) of IR (EU) 2025/2620), so imported electricity is charged on its full embedded emissions from 2026. What differs between the other sectors is the benchmark and the embedded emissions of each product and production route, which determine the absolute cost impact. Cement and fertilizers include indirect emissions (electricity consumption during production) in the CBAM obligation calculation, while iron and steel, aluminium, hydrogen, and electricity cover only direct emissions, except agglomerated iron ore (CN 2601 12 00), whose indirect emissions count.
Does Free Allocation Reduction Affect Article 9 Carbon Price Deductions?
The Article 9 reduction (for a carbon price effectively paid in the country of origin) is a separate term in the certificate formula. It is subtracted alongside the free allocation adjustment, and the result cannot fall below zero. A reduction may be claimed only for a price effectively paid, with any rebate or compensation taken into account (Article 9(1)). Where default values are used, it may be claimed only by reference to yearly default carbon prices that the Commission may set from 2027 (Article 9(4)). As of October 12, 2026 the implementing act is still a draft and no country's carbon price has been recognised.
What CBAM Compliance Steps Should Importers Complete Before 2030?
The 6 compliance steps most critical before the 2029-to-2030 cost acceleration are listed below.
- Hold authorized CBAM declarant status (the March 31, 2026 application deadline for provisional importing under Article 17(7a) has passed).
- Establish supplier data flows for embedded emissions reporting at production installation level.
- Arrange verifier contracts early if you plan to declare actual values: verifier registration opened on September 1, 2026, and seven verification bodies were documented as accredited by November 12, 2026, by five national accreditation bodies (ESYD in Greece, Accredia in Italy, Swedac in Sweden, RvA in the Netherlands and BELAC in Belgium), with the Commission's official list still unpublished.
- Model CBAM costs across the full 2026-to-2034 schedule with the legal formula, using a range of ETS price scenarios.
- Renegotiate supply contracts with CBAM cost escalation clauses tied to the published CBAM factor schedule.
- Track the Article 9 implementing act on carbon prices paid in countries of origin, which was still a draft on October 12, 2026.
Detailed guidance for each step is available in the CBAM compliance for importers section.