The CBAM calculation determines how many certificates an EU importer must purchase and surrender for each tonne of carbon-intensive goods brought into the EU. The core formula is: CBAM certificates = max[0; SEE minus SEFA minus carbon price term] × quantity (tonnes), and the cost is certificates × certificate price (€/tCO₂e).
SEE is the specific embedded emissions of the good, SEFA its specific embedded free allocation and the carbon price term the Article 9 reduction, each in tCO₂e per tonne.
The official certificate prices for 2026 are €75.36/tCO₂e for Q1, €75.28 for Q2 and €82.32 for Q3 (published October 5, 2026), each the quarterly average of EU ETS auction prices under Article 21(1a) of Regulation (EU) 2023/956.
Six sectors fall within scope: iron and steel, cement, aluminium, fertilizers, electricity, and hydrogen. Understanding the CBAM calculation before the first declaration deadline of September 30, 2027 protects importers from the Article 26(1) penalty: €100 per tonne CO₂e before inflation indexation for each certificate not surrendered.
This guide covers the six-step calculation process under Regulation (EU) 2023/956 as amended by Regulation (EU) 2025/2083, with worked examples for all six sectors, a cost reference table, and answers to the questions importers most commonly ask about EU CBAM compliance.
What the CBAM Calculation Measures
CBAM calculation measures the embedded greenhouse gas emissions in imported goods and converts those emissions into a financial obligation priced at the EU ETS carbon price.
The calculation does not produce a customs duty or a tax on revenue. It produces a certificate quantity: one CBAM certificate for each tonne of CO₂e that remains after the free allocation adjustment and any Article 9 reduction.
The legal basis for the embedded emissions methodology is Article 7 of Regulation (EU) 2023/956, supplemented in full technical detail by Implementing Regulation (EU) 2025/2547.
Two quantities drive the CBAM embedded emissions side of every CBAM calculation: the specific embedded emissions (SEE) of the goods, expressed in tCO₂e per tonne of product, and the net mass of the import in tonnes. Article 31 and Implementing Regulation (EU) 2025/2620 add a third quantity, the free allocation adjustment.
Three types of emissions enter the calculation depending on the sector:
- Direct embedded emissions: Greenhouse gases from the production process itself, including heat and cooling consumed during production (Article 3(21), Regulation (EU) 2023/956). Priced in all six sectors.
- Indirect embedded emissions: Emissions from electricity consumed during production (Article 3(34)). Priced only for cement and fertilizers.
- Precursor embedded emissions: Embedded emissions carried forward from Annex I inputs used to produce complex goods. Relevant for steel pipes (using hot-rolled coil as precursor) and cement (using clinker as precursor).
The free allocation adjustment reduces the certificates to reflect the free EU ETS allowances that EU producers of the same good still receive (Article 31 of Regulation (EU) 2023/956).
The legal CBAM factor is the share of free allocation retained: 97.5% in 2026 under Article 10a(1a) of Directive 2003/87/EC, so 2.5% of free allocation is phased out in 2026.
The adjustment per tonne (SEFA) is the CBAM factor × the cross-sectoral correction factor × the CBAM benchmark of the good, and it is subtracted from the SEE.
The net obligation is therefore not 2.5% of the gross figure. Only a good whose emissions equal its benchmark pays 2.5% of gross in 2026; every tonne of CO₂e above the benchmark is charged in full, and a good below 97.5% of its benchmark owes nothing.
The gross CBAM calculation (SEE × quantity × price) still matters for planning: it is the ceiling the cost approaches as the CBAM factor falls, and no CBAM factor applies from 2034.
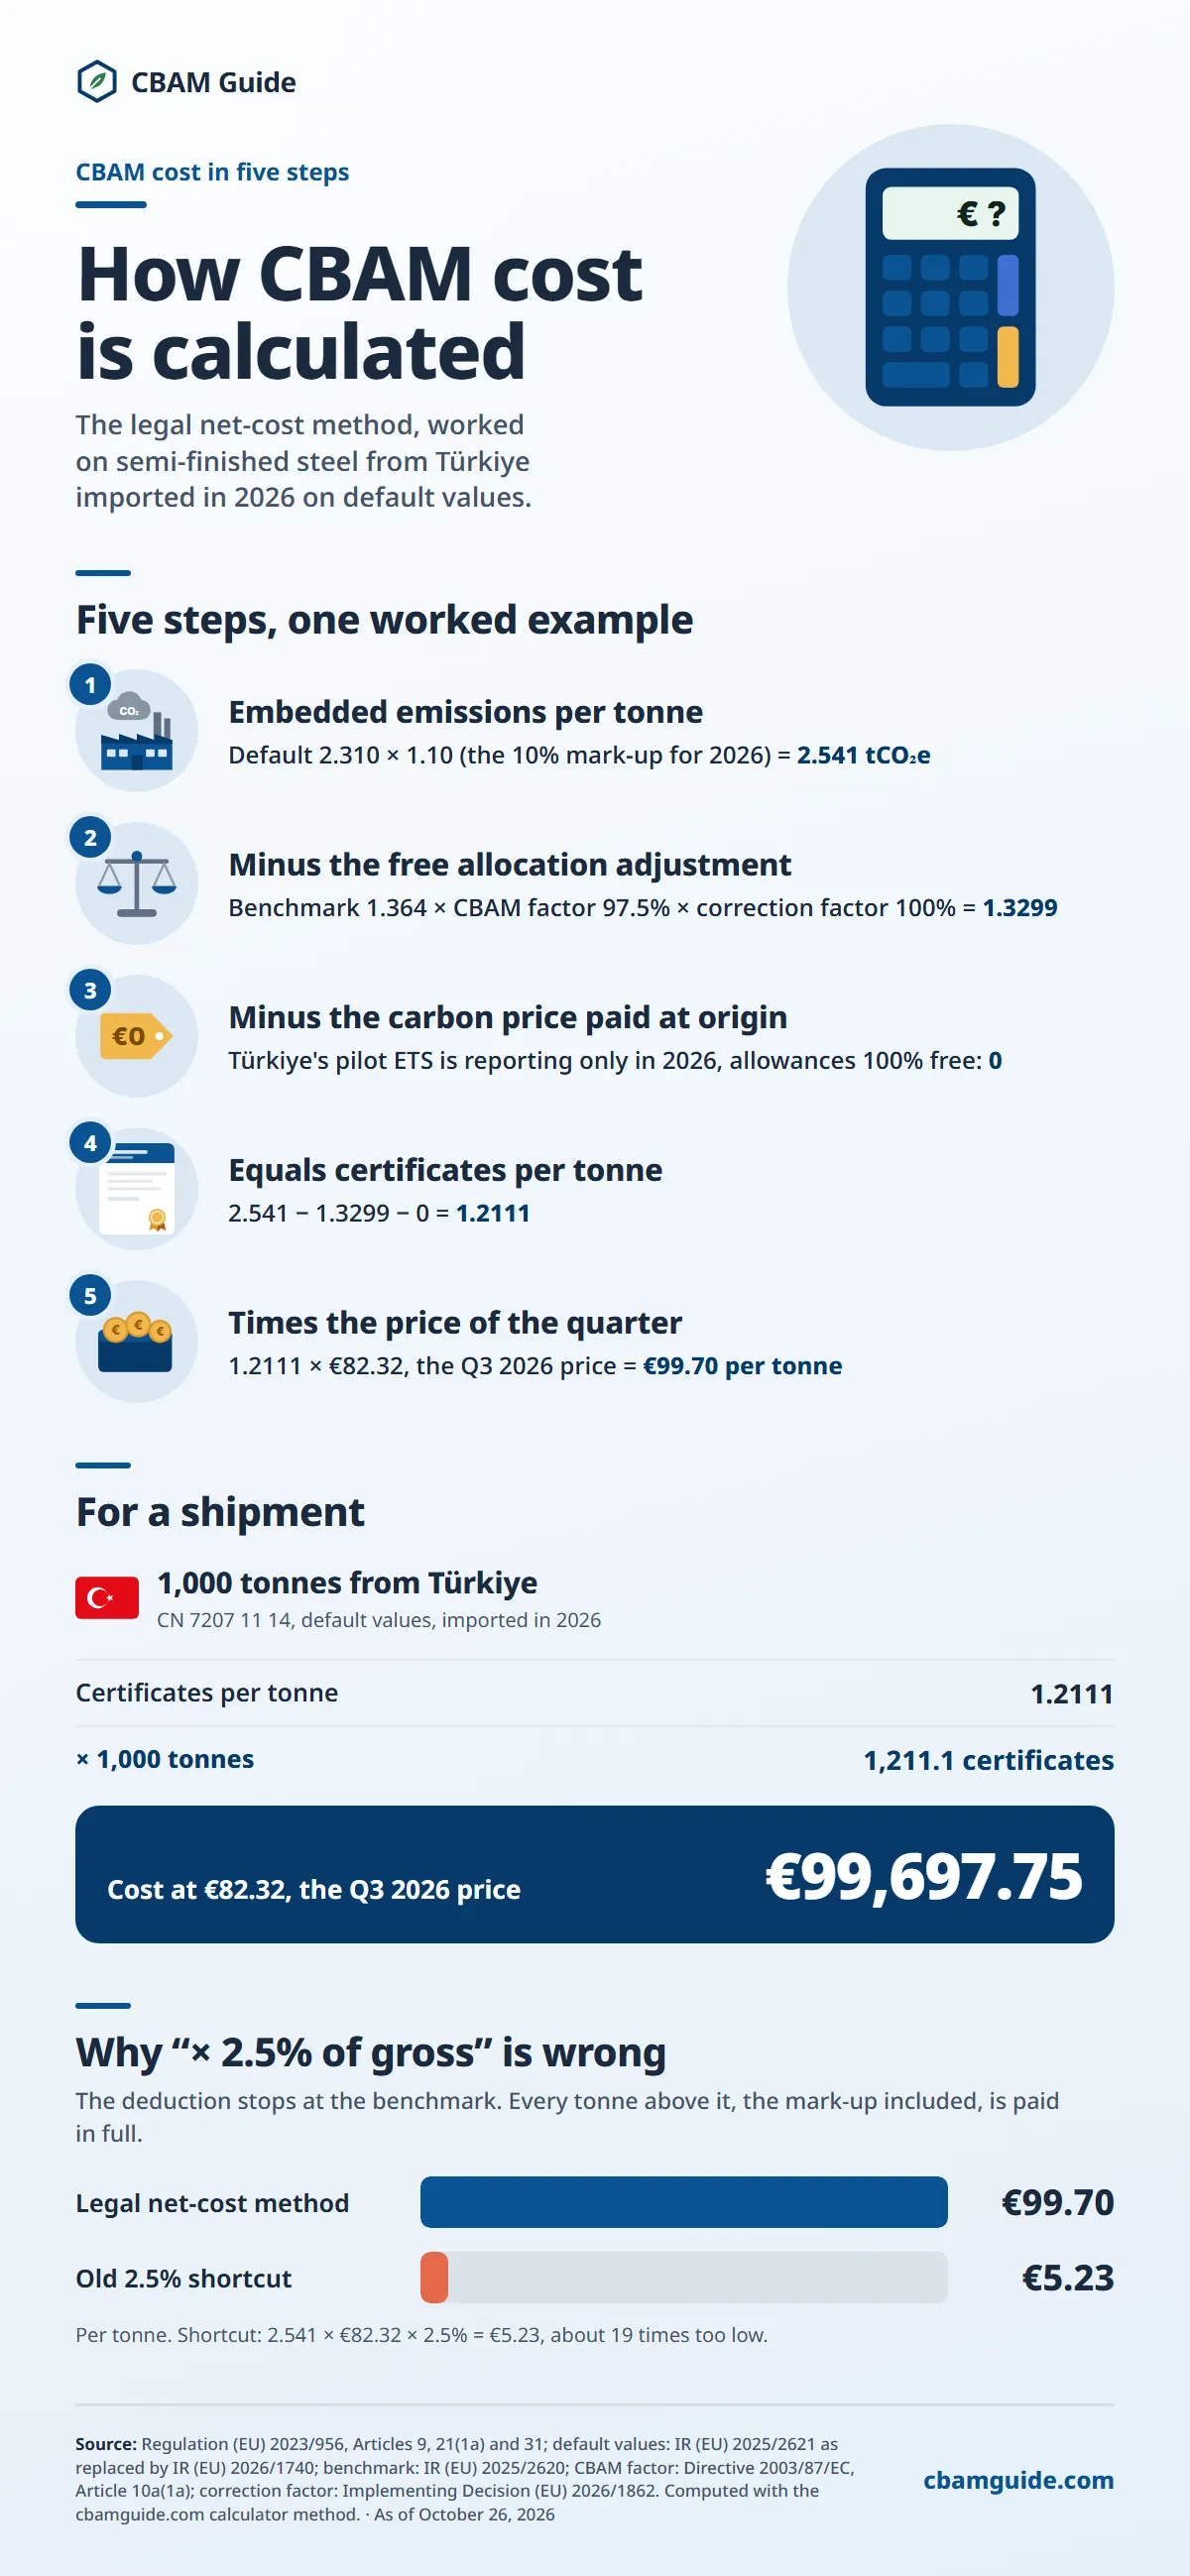
Text version of this infographic
Five steps, one worked example
1. Embedded emissions per tonne: Default 2.310 × 1.10 (the 10% mark-up for 2026) = 2.541 tCO₂e
2. Minus the free allocation adjustment: Benchmark 1.364 × CBAM factor 97.5% × correction factor 100% = 1.3299
3. Minus the carbon price paid at origin: Türkiye's pilot ETS is reporting only in 2026, allowances 100% free: 0
4. Equals certificates per tonne: 2.541 − 1.3299 − 0 = 1.2111
5. Times the price of the quarter: 1.2111 × €82.32, the Q3 2026 price = €99.70 per tonne
For a shipment
1,000 tonnes from Türkiye (CN 7207 11 14, default values, imported in 2026)
- Certificates per tonne: 1.2111
- × 1,000 tonnes: 1,211.1 certificates
Cost at €82.32, the Q3 2026 price: €99,697.75
Why “× 2.5% of gross” is wrong
The deduction stops at the benchmark. Every tonne above it, the mark-up included, is paid in full.
- Legal net-cost method: €99.70
- Old 2.5% shortcut: €5.23
Per tonne. Shortcut: 2.541 × €82.32 × 2.5% = €5.23, about 19 times too low.
How to Calculate CBAM Obligations: 6 Steps
The six steps below follow the importer compliance chain established under Regulation (EU) 2023/956 and IR (EU) 2025/2547. Each step produces a specific output that feeds the next step. Completing all six steps produces the final CBAM certificate obligation for the annual declaration.
Step 1: Identify the CN Code and Covered Sector
Every CBAM calculation starts with the Combined Nomenclature (CN) code of the imported product. The CN code determines whether the good falls under Annex I of Regulation (EU) 2023/956 and which of the six sectors applies.
Annex I has 42 entries across the six sectors, listed below. An entry at chapter or heading level covers every 8-digit CN code beneath it; the CBAM goods list gives each entry with its description. A good not listed in Annex I carries no CBAM obligation regardless of its carbon content.
| Sector | Annex I entries | Direct Emissions | Indirect Emissions |
|---|---|---|---|
| Iron and steel (15 entries) | Chapter 72, except ferrous scrap (7204) and the ferro-alloys of heading 7202 other than ferro-manganese, ferro-chromium and ferro-nickel; 2601 12 00 (agglomerated iron ore); 7301, 7302, 7303 00, 7304, 7305, 7306, 7307, 7308, 7309 00, 7310, 7311 00, 7318, 7326 | Priced | Not priced, except for 2601 12 00 |
| Cement (6 entries) | ex 2507 00 80 (calcined clay only), 2523 10 00, 2523 21 00, 2523 29 00, 2523 30 00, 2523 90 00 | Priced | Priced |
| Aluminium (14 entries) | 7601, 7603, 7604, 7605, 7606, 7607, 7608, 7609 00 00, 7610, 7611 00 00, 7612, 7613 00 00, 7614, 7616 | Priced | Not priced |
| Fertilizers (5 entries) | 2808 00 00, 2814, 2834 21 00, 3102, 3105 (except 3105 60 00) | Priced | Priced |
| Electricity | 2716 00 00 only | Priced | N/A |
| Hydrogen | 2804 10 00 only | Priced | Not priced |
Two exemptions remove goods from scope even when the CN code matches. First, the 50-tonne de minimis exemption of Article 2a: an importer whose CBAM goods do not cumulatively exceed 50 tonnes of net mass in a calendar year (the threshold in point 1 of Annex VII) faces no obligation.
Electricity and hydrogen have no threshold and are never exempt. Second, goods originating in Annex III countries, specifically Iceland, Liechtenstein, Norway, and Switzerland, are exempt because the EU ETS applies there or their emissions trading system is fully linked to it (Article 2(6)).
Step 2: Determine the Production Route
The production route matters in two ways. On actual values, it fixes the system boundary and the monitoring rules that the installation applies under IR (EU) 2025/2547, and the operator's emissions report states it.
On default values, the importer does not choose a route: the route letter printed in the country's row of Annex I to IR (EU) 2025/2621 selects the CBAM benchmark for the free allocation adjustment in Step 4 (point 5.1 of the Annex to IR (EU) 2025/2620).
The benchmarks show how far the routes differ. The table below lists the Column B default benchmark for main goods of each sector, from point 5.3 of the Annex to IR (EU) 2025/2620.
| Sector | Good (CN code) | Route indicator | Column B benchmark (tCO₂e/t) |
|---|---|---|---|
| Iron and steel | Semi-finished carbon steel (7207 11 14) | (C) BF/BOF | 1.364 |
| Iron and steel | Semi-finished carbon steel (7207 11 14) | (D) DRI/EAF | 0.475 |
| Iron and steel | Semi-finished carbon steel (7207 11 14) | (E) scrap/EAF | 0.066 |
| Cement | Grey Portland cement (2523 29 00) | None | 0.666 |
| Cement | White Portland cement (2523 21 00) | None | 0.859 |
| Aluminium | Unwrought aluminium (7601) | (K) primary | 1.423 |
| Aluminium | Unwrought aluminium (7601) | (L) secondary | 0.091 |
| Fertilizers | Urea (3102 10 19) | None | 0.902 |
| Fertilizers | Anhydrous ammonia (2814 10 00) | None | 1.522 |
| Hydrogen | Hydrogen (2804 10 00) | None | 5.089 |
| Electricity | Electrical energy (2716 00 00) | None | No benchmark: the adjustment is zero |
A benchmark is the value deducted in the free allocation adjustment, not the emission intensity of a real plant. The SEE comes from Step 3: the verified actual values of the installation, or the Annex I default for the country of origin and CN code.
Step 3: Obtain Specific Embedded Emissions (Actual or Default)
Specific embedded emissions (SEE) are expressed in tCO₂e per tonne of goods and are the starting quantity of the CBAM certificate calculation. Importers obtain SEE data through one of two paths.
Path A: Actual verified emissions arrive from the non-EU production installation. The producer prepares a monitoring plan, measures or calculates emissions per IR (EU) 2025/2547, and provides the SEE figure alongside supporting documentation.
This data must be verified by an accredited verifier under DR (EU) 2025/2551. Verified actual emissions are the preferred path because default values carry a punitive mark-up.
Path B: Default values from IR (EU) 2025/2621, as corrected by IR (EU) 2026/1740 with effect from January 1, 2026, apply when actual data is unavailable. Default values are set per country of origin and CN code.
The "total emissions" value is increased by a mark-up of 10% for 2026, 20% for 2027, and 30% from 2028 onward; fertilizers carry 1% in every year. The mark-up is applied before the free allocation deduction and the benchmark carries none, so every marked-up tonne of CO₂e is charged at the full certificate price.
For the methodology behind Path A, the Commission's own support material is now available. On August 14, 2026, DG TAXUD published ten guidance documents for the definitive period on the CBAM legislation and guidance page, including Guidance No 3 on methods for calculating embedded emissions and sector guidance 5a–5f for cement, hydrogen, fertilizers, iron and steel, aluminium, and electricity.
The guidance is non-binding support material for the 2026 reporting year (first declarations due September 30, 2027); the overview of all ten guidance documents covers what each contains.
One important planning note: the two paths use different benchmarks in the SEFA (Specific Embedded Free Allocation) methodology. On default values, the deduction uses the default CBAM benchmark in Column B of point 5 of the Annex to IR (EU) 2025/2620.
On actual values, it uses the Column A process benchmark plus the free allocation embedded in precursors. The net result can therefore differ by more or less than the gap in emissions. Importers should model both paths before deciding.
Step 4: Apply the CBAM Formula
The CBAM calculation formula combines Articles 7, 9 and 31 of Regulation (EU) 2023/956, as Article 6(2)(c) requires. The Commission's Guidance No 1 of August 14, 2026 (non-binding, section 2.4.2) states it as:
CBAM certificates = max[0; SEE minus SEFA minus carbon price term] × Quantity (tonnes)
CBAM obligation (€) = CBAM certificates × certificate price (€/tCO₂e)
The terms of the formula are listed below.
- SEE: specific embedded emissions in tCO₂e per tonne, actual or default with mark-up (Article 7).
- SEFA: specific embedded free allocation in tCO₂e per tonne (Article 31; Annex to IR (EU) 2025/2620, Equations 1 to 6). On default values, SEFA = CBAM factor × cross-sectoral correction factor (CSCF) × the default CBAM benchmark in point 5, Column B (Equation 6). On actual values, the Column A process benchmark applies, plus the adjustment embedded in precursors (Equations 2 to 4).
- CBAM factor: 97.5% for 2026, the share of free allocation retained (Article 10a(1a) of Directive 2003/87/EC).
- CSCF: 100% for each year from 2026 to 2030 (Implementing Decision (EU) 2026/1862, Article 1).
- Carbon price term: the carbon price effectively paid in the country of origin per tonne of good, divided by the certificate price (Article 9; the implementing act on this conversion was still a draft on October 12, 2026).
- max[0; ...]: a negative result counts as zero, so a good at or below 97.5% of its benchmark owes no certificates in 2026.
The free allocation adjustment for electricity is zero (Article 1(2) of IR (EU) 2025/2620), so imported electricity is charged on its full embedded emissions.
The certificate price for 2026 emissions is the quarterly average of the closing prices of EU ETS allowances on the auction platform for the quarter of importation (Article 21(1a); IR (EU) 2025/2548).
From 2027 it is the weekly average (Article 21(1)). The official prices so far are €75.36/tCO₂e for Q1 2026, €75.28 for Q2 and €82.32 for Q3, the last published on October 5, 2026.
The table below shows gross and net 2026 costs per tonne for five goods on default values. The defaults are the "total emissions" values of Annex I to IR (EU) 2025/2621, as replaced by IR (EU) 2026/1740, and the benchmarks are the Column B values of IR (EU) 2025/2620.
Gross is the default plus mark-up × price, before the SEFA deduction; net is the legal obligation at the official price of each quarter of 2026 published so far.
| Origin and good (CN code) | Default plus 2026 mark-up (tCO₂e/t) | Benchmark | Certificates per tonne | Gross at €82.32 | Net at €75.36 (Q1) | Net at €75.28 (Q2) | Net at €82.32 (Q3) |
|---|---|---|---|---|---|---|---|
| Türkiye, semi-finished steel (7207 11 14) | 2.541 | 1.364 | 1.2111 | €209.18 | €91.27 | €91.17 | €99.70 |
| Egypt, grey Portland cement (2523 29 00) | 1.419 | 0.666 | 0.76965 | €116.81 | €58.00 | €57.94 | €63.36 |
| United Arab Emirates, unwrought aluminium (7601) | 2.057 | 1.423 | 0.669575 | €169.33 | €50.46 | €50.41 | €55.12 |
| Egypt, urea (3102 10 19) | 1.4039 | 0.902 | 0.52445 | €115.57 | €39.52 | €39.48 | €43.17 |
| Türkiye, hydrogen (2804 10 00) | 11.902 | 5.089 | 6.940225 | €979.77 | €523.02 | €522.46 | €571.32 |
Certificates per tonne = default plus mark-up, minus 0.975 × 1.00 × benchmark. Costs are calculated from unrounded certificate numbers. Net cost is not a fixed percentage of gross cost. Electricity has no Annex I default value and no free allocation adjustment.
Worked example for Turkish BF-BOF steel billets on default values (CN 7207 11 14, imported in Q3 2026):
- Default value: 2.310 tCO₂e/t (IR (EU) 2026/1740, Annex I, Türkiye, production route (C))
- SEE with the 10% mark-up: 2.310 × 1.10 = 2.541 tCO₂e/t
- Default CBAM benchmark: 1.364 tCO₂e/t (IR (EU) 2025/2620, point 5.3, Column B, route (C), carbon steel via blast furnace and basic oxygen furnace)
- SEFA: 0.975 × 1.00 × 1.364 = 1.3299 tCO₂e/t
- Certificates per tonne: 2.541 minus 1.3299 = 1.2111
- Quantity: 500 tonnes, so 605.55 certificates
- Certificate price: €82.32/tCO₂e (official Q3 2026 price)
- Gross CBAM cost: 2.541 × 500 × €82.32 = €104,587.56
- Net 2026 obligation: 605.55 × €82.32 = €49,848.88, or €99.70 per tonne
The net figure is 47.7% of gross, not 2.5%: a flat 2.5% of gross would give €5.23 per tonne against the €99.70 actually owed.
On the same default value, benchmark and price, the cost rises to €189.38 per tonne for 2030 imports, when the mark-up is 30% and the CBAM factor 51.5%. Planning for the 2029–2030 free allocation cliff is the most important financial decision EU importers of steel face today.
Step 5: Calculate the Quarterly Holding Requirement
The quarterly holding requirement under Article 22(2) of Regulation (EU) 2023/956, as amended by Regulation (EU) 2025/2083, applies from 2027. At the end of each calendar quarter, the importer's CBAM Registry account must hold certificates corresponding to at least 50% of the embedded emissions in all goods imported since January 1 of that year.
The emissions are determined on one of the two bases below, and the free allocation adjustment of Article 31 is taken into account.
- Basis (a): default values without the mark-up.
- Basis (b): the number of certificates surrendered for the previous calendar year, where the imports are the same goods by CN code and country of origin.
This requirement prevents importers from deferring all purchases to the annual declaration deadline. Where the account falls short, the competent authority notifies the importer, who then has one month to hold enough certificates (Article 22(3)).
Calculation method for quarterly holding on basis (a):
- Sum the mass of each CBAM good imported from January 1 to the end of the relevant quarter (Q1, Q2, Q3, or Q4)
- Multiply each mass by the default value without mark-up, less the SEFA for that year
- Multiply by 0.50 to obtain the 50% threshold
- Compare that figure to current certificate holdings in the CBAM Registry account and purchase any shortfall before quarter-end
Example: An importer brings in 1,000 tonnes of Turkish steel billets (CN 7207 11 14) in Q1 2027 and 800 tonnes in Q2 2027. The default value without mark-up is 2.310 tCO₂e/t.
With the 2027 CBAM factor of 95%, SEFA = 0.95 × 1.00 × 1.364 = 1.2958 tCO₂e/t, which leaves 1.0142 tCO₂e/t. By end of Q2, 1,800 tonnes × 1.0142 = 1,825.56 tCO₂e. Deducting the adjustment in full before the 50% is taken, the holding requirement is 913 CBAM certificates by June 30, 2027.
Step 6: Purchase Certificates and Surrender at Declaration
CBAM certificate sales open February 1, 2027 on the common central platform. Certificates are not traded on an exchange. Each certificate corresponds to one tonne of CO₂e.
Certificates for 2026 emissions carry the official price of the quarter in which the goods were imported (Article 21(1a)); from 2027 the price is the weekly average (Article 21(1)).
The annual CBAM declaration, due September 30, 2027 for calendar year 2026 imports, requires surrender of the certificates calculated in Step 4: the embedded emissions after the Article 9 reduction and the Article 31 free allocation adjustment (Article 6(2)(c) and Article 22(1)).
The six inputs for the declaration, built on Article 6(2) of Regulation (EU) 2023/956 and its supporting detail, are listed below.
- Total quantity of CBAM goods imported during the calendar year, broken down by CN code and country of origin
- Total embedded emissions (tCO₂e), verified where actual values are used and broken down by goods type and origin country
- Total CBAM certificates to be surrendered, after the Article 9 reduction and the free allocation adjustment
- Carbon price paid in any country of origin where an Article 9 deduction is claimed
- Verification reports supporting the actual embedded emissions figures
- The SEFA figures behind the free allocation adjustment, including the CBAM benchmark used for each good
The repurchase (buyback) provision lets an importer ask for excess certificates to be bought back at the original purchase price, with the request due by October 31 of the surrender year (Article 23(1) and (3)).
The number is limited to the certificates the importer was obliged to purchase under Article 22(2) during the calendar year of purchase (Article 23(2)); certificates purchased in 2027 for 2026 emissions may only be repurchased in 2027 (Article 23(2a)). This provides a hedge against over-purchasing when import volumes fall short of projections.
All official CBAM default values in one spreadsheet, with mark-up, benchmark and 2026 cost per tonne. Instant download.
We store only your email address for these alerts. Privacy policy
CBAM Calculation Examples for All 6 Sectors
The six worked examples below apply the formula to a 1,000-tonne shipment imported in Q3 2026 on default values, at the official Q3 2026 certificate price of €82.32/tCO₂e, showing both gross and net 2026 costs.
Each default value is the "total emissions" figure in Annex I to IR (EU) 2025/2621, as replaced by IR (EU) 2026/1740. Each benchmark comes from point 5.3, Column B, of the Annex to IR (EU) 2025/2620, and SEFA = 0.975 × 1.00 × benchmark.
Steel (BF-BOF billets from Türkiye, CN 7207 11 14): default 2.310 tCO₂e/t, with the 10% mark-up 2.541. Benchmark 1.364 (route (C)), SEFA 1.3299. Certificates = (2.541 minus 1.3299) × 1,000 = 1,211.1. Gross obligation = €209,175.12. Net 2026 = €99,697.75.
Cement (grey Portland from Egypt, CN 2523 29 00): default 1.290 tCO₂e/t, with the 10% mark-up 1.419. Both direct and indirect emissions are priced. Benchmark 0.666, SEFA 0.6494. Certificates = 769.65. Gross obligation = €116,812.08. Net 2026 = €63,357.59.
Aluminium (primary unwrought from the United Arab Emirates, CN 7601): default 1.870 tCO₂e/t, with the 10% mark-up 2.057 (direct emissions only; indirect electricity emissions are not priced by CBAM for aluminium). Benchmark 1.423 (route (K)), SEFA 1.3874. Certificates = 669.58. Gross obligation = €169,332.24. Net 2026 = €55,119.41.
Fertilizers (urea from Egypt, CN 3102 10 19): default 1.390 tCO₂e/t, with the 1% fertilizer mark-up 1.4039. Both direct and indirect emissions are priced. Benchmark 0.902, SEFA 0.8795. Certificates = 524.45. Gross obligation = €115,569.05. Net 2026 = €43,172.72.
Electricity: Obligation is expressed per MWh, not per tonne, and the free allocation adjustment is zero (Article 1(2) of IR (EU) 2025/2620), so gross and net are the same. For an illustrative 1,000 MWh at an emission factor of 0.5 tCO₂/MWh, the obligation is 500 certificates, or 500 × €82.32 = €41,160.
Hydrogen (from Türkiye, CN 2804 10 00): default 10.820 tCO₂e/t, with the 10% mark-up 11.902. Benchmark 5.089, SEFA 4.9618. Certificates = 6,940.23. Gross obligation = €979,772.64. Net 2026 = €571,319.32.
On actual values the Column A benchmark is also 5.089, so hydrogen with a verified SEE at or below 4.962 tCO₂e/t, green hydrogen included, owes no certificates in 2026.
In these examples the net obligation runs from 33% to 58% of the gross figure. The exact share depends on how far the declared emissions sit above the benchmark listed for the CN code and production route.
What Happens When Calculation Data Is Unavailable
Importers who cannot obtain actual embedded emissions data from their non-EU suppliers fall back on the default value system established in IR (EU) 2025/2621, as corrected by IR (EU) 2026/1740.
The CBAM default values system provides country-specific and product-specific emission intensity figures that serve as the SEE in the formula when verified actual data is absent.
Default values are set at the average emission intensity for the product in the country of origin, then marked up. The mark-up schedule increases the punitive element over time: 10% in 2026, 20% in 2027, and 30% from 2028 onward.
Fertilizer defaults carry a 1% mark-up for 2026 and onwards, under the introductory part of Annex I. The practical effect is that importers paying default-based CBAM costs pay progressively more than importers with actual verified data as the years advance.
Exporters whose actual emissions fall below the country default face a strong financial incentive to invest in monitoring systems, provide verified data to their EU customers, and reduce their embedded emissions. The mark-up is charged in full, because the free allocation deduction does not grow with the emissions declared.
For Turkish steel billets (CN 7207 11 14, default 2.310 tCO₂e/t), the 2026 mark-up adds 0.231 tCO₂e per tonne, or €19.02 per tonne at €82.32/tCO₂e. From 2028 the 30% mark-up adds 0.693 tCO₂e, or €57.05 per tonne at the same price.
How CBAM Calculation Interacts with the EU ETS and Free Allocation
The CBAM calculation does not operate in isolation from the EU ETS. Two interactions directly affect the net cost importers face.
The Free Allocation Phase-Out
EU ETS free allocation for CBAM sectors reduces the CBAM certificate obligation, as required by Article 31 of Regulation (EU) 2023/956 and calculated through the SEFA methodology established in IR (EU) 2025/2620.
The CBAM factor is the share of free allocation that EU producers retain, set by Article 10a(1a) of Directive 2003/87/EC. As it falls, SEFA shrinks and the net certificate obligation rises.
The table below applies the schedule to the Turkish billet example (CN 7207 11 14 on default values, benchmark 1.364, CSCF 100%) at a constant €82.32/tCO₂e. The CSCF is set only to 2030, so SEFA for 2031 to 2033 cannot yet be calculated.
| Year | CBAM factor (free allocation retained) | Share phased out | Default mark-up | SEFA (tCO₂e/t) | Certificates per tonne | Net cost per tonne |
|---|---|---|---|---|---|---|
| 2026 | 97.5% | 2.5% | 10% | 1.3299 | 1.2111 | €99.70 |
| 2027 | 95% | 5% | 20% | 1.2958 | 1.4762 | €121.52 |
| 2028 | 90% | 10% | 30% | 1.2276 | 1.7754 | €146.15 |
| 2029 | 77.5% | 22.5% | 30% | 1.0571 | 1.9459 | €160.19 |
| 2030 | 51.5% | 48.5% | 30% | 0.7025 | 2.3005 | €189.38 |
| 2031 | 39% | 61% | 30% | not yet set | n/a | n/a |
| 2032 | 26.5% | 73.5% | 30% | not yet set | n/a | n/a |
| 2033 | 14% | 86% | 30% | not yet set | n/a | n/a |
| From 2034 | No CBAM factor applies | 100% | 30% | 0 | 3.0030 | €247.21 |
The steepest increase occurs between 2029 and 2030, when the CBAM factor drops from 77.5% to 51.5%.
An importer of 10,000 tonnes of these billets per year would see the net annual CBAM cost rise from approximately €997,000 for 2026 imports to approximately €1.89 million for 2030 imports. No change in import volume or certificate price is required for this increase to occur.
The share phased out equals the net obligation as a share of gross in one case only: a good whose embedded emissions exactly equal its benchmark. Such a good pays 2.5% of gross in 2026 and 48.5% in 2030.
Emissions above the benchmark, including the whole default mark-up, are charged in full in every year. The CBAM cost model template page explains this legal method and links the cost calculator, which applies it to the official default values and benchmarks for a chosen country of origin and CN code.
Guidance No 4, on the calculation of the free allocation adjustment to the certificates to be surrendered, is the Commission's reference document for this adjustment, published August 14, 2026 as part of the ten definitive-period guidance documents. It is non-binding support material for the 2026 reporting year.
The Article 9 Carbon Price Deduction
An authorized declarant may claim a reduction in the number of certificates for a carbon price effectively paid in a third country on the declared embedded emissions (Article 9(1) of Regulation (EU) 2023/956).
Any rebate or other compensation available in that country is taken into account, so allowances allocated free of charge are not a price paid.
The regulation attaches documentation duties. The declarant keeps records showing that the price was effectively paid, certified by a person independent of the declarant and of the third-country authorities, until the end of the fourth year after the year of the declaration (Article 9(2) and (3)).
Where default values are used, a reduction can be claimed only by reference to yearly default carbon prices, which the Commission may set from 2027 (Article 9(4)).
As of October 12, 2026, no country's carbon price has been recognised under Article 9. The Commission published a draft Implementing Regulation on May 13, 2026 setting out four recognition pathways (ETS, point-source carbon taxes, fuel-based carbon taxes, and mixed-compliance systems), and the measure is still a draft after its public consultation closed June 10, 2026.
That holds for every origin, including South Korea, the United Kingdom, China, India and Türkiye. Goods originating in Switzerland need no deduction: they are outside CBAM under Annex III.
The CBAM regulation legal basis under Article 192(1) TFEU classifies CBAM as an environmental measure, not a trade measure. This distinction affects how Article 9 deductions interact with WTO obligations, a question that remains unsettled in the ongoing dispute WTO DS639 (Russia vs EU, 2025).
Frequently Asked Questions on CBAM Calculation
What is the formula for CBAM calculation?
The CBAM calculation formula is: CBAM certificates = max[0; SEE minus SEFA minus carbon price term] × Quantity (tonnes), and the CBAM obligation in euros is the certificates × the certificate price (€/tCO₂e). SEE is the specific embedded emissions figure, which comes from verified actual data from the production installation or, if unavailable, from Commission default values published in IR (EU) 2025/2621 as corrected by IR (EU) 2026/1740. SEFA is the free allocation adjustment per tonne: the CBAM factor (97.5% for 2026) × the cross-sectoral correction factor (100% for 2026 to 2030) × the CBAM benchmark listed for the good in the Annex to IR (EU) 2025/2620. The carbon price term is the Article 9 reduction.
Does CBAM calculation use the same emission factor for all countries?
No. The CBAM calculation uses production-installation-specific embedded emissions, not country averages. Default values are country-specific (per IR (EU) 2025/2621), but actual verified data from the specific facility overrides any country average. A BF-BOF steel producer in Turkey operating a modern, efficient plant may have lower actual SEE than the Turkish country default.
Is the CBAM calculation different for steel versus cement?
Yes. Steel CBAM calculation covers direct emissions only (CO₂). Cement CBAM calculation covers both direct and indirect emissions (including electricity consumption in the production process). Cement is one of two sectors where indirect emissions are priced under CBAM; the other is fertilizers. This makes cement's SEE data requirements more complex, as importers must obtain both the direct emission figure and the electricity consumption data from the production installation.
Can an importer use default values for the CBAM calculation?
Yes, but with a financial penalty. Default values from IR (EU) 2025/2621 are available when actual verified data cannot be obtained. They carry a mark-up of 10% in 2026, rising to 30% from 2028 onward (1% for fertilizers). The CBAM steel sector example illustrates how the gap between default and actual values can translate into material cost differences as free allocation phases out.
Does the 50-tonne de minimis exemption affect the CBAM calculation?
The de minimis threshold exempts small importers entirely from CBAM obligations, meaning no calculation is required if total annual imports across all CBAM goods (excluding electricity and hydrogen) do not exceed 50 tonnes of net mass per importer per calendar year (Article 2a; Annex VII, point 1). The threshold applies per importer, not per shipment or per commodity type. Importers above the threshold must perform the full CBAM calculation for all their covered imports.
Do CBAM calculations change quarterly?
The embedded emissions figure used in the annual declaration does not change quarterly. From 2027, the quarterly holding requirement of Article 22(2) forces importers to track imports throughout the year and hold certificates for at least 50% of the embedded emissions imported since January 1, after the free allocation adjustment, at each quarter-end. The price does vary by quarter for 2026: certificates for 2026 emissions carry the official average price of the quarter of importation under Article 21(1a), published by the Commission under IR (EU) 2025/2548.
How Does CBAM Calculation Differ for the Six Sectors?
The six sectors covered by CBAM use the same core formula but differ in which emission types are included in the SEE figure and which GHGs are counted.
Does the CBAM calculation cover perfluorocarbons (PFCs) from aluminium?
Yes. For aluminium, the SEE includes both CO₂ from anode consumption and PFC emissions (CF₄ with GWP of 6,630, and C₂F₆ with GWP of 11,100) from anode effect events during Hall-Héroult smelting. PFCs are converted to CO₂e for the CBAM calculation using their global warming potential values. Primary aluminium producers with higher rates of anode effect events carry higher SEE figures and thus higher CBAM certificate obligations. The benchmarks show the distance between the two routes: 1.423 tCO₂e/t for primary and 0.091 for secondary unwrought aluminium (Column B, IR (EU) 2025/2620).
Is the CBAM calculation for green hydrogen zero?
It can be, on verified actual values. Hydrogen is listed in Annex II of Regulation (EU) 2023/956, so only direct emissions count and the electricity used in electrolysis is not part of the SEE. In 2026 the free allocation adjustment for hydrogen is 0.975 × 5.089 = 4.962 tCO₂e/t on both paths, so hydrogen with a verified SEE at or below that figure owes no certificates. Without verified data the country default applies whatever the production method: 10.820 tCO₂e/t for Türkiye before the mark-up. The CBAM sectors article covers the full requirements for each of the six sectors.